HomeCategory

Tax Controversy

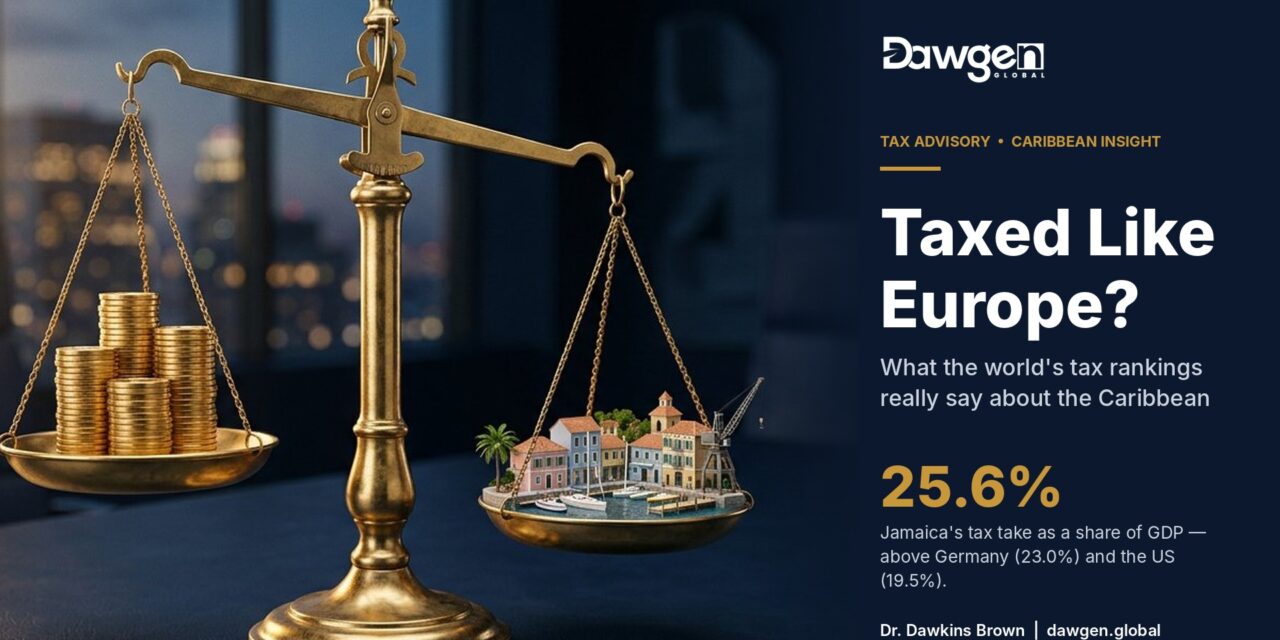
Taxed Like Europe?  What the World’s Tax Rankings Really Say About the Caribbean

The finding Jamaica collects tax equal to 25.6% of its GDP — more, as a share of its economy, than the United States (19.5%), Germany (23.0%), Japan (20.2%) or Switzerland (20.0%). Barbados, at 27.8%, collects more than Greece and sits on the global top-20 list beside the Nordic welfare states. That is the Caribbean story...
What Digital Tax Means for Caribbean Retail and Manufacturing

Retailers and manufacturers now buy software, advertising and cloud capacity from abroad and sell through websites, marketplaces and chat apps. Digital tax reaches both sides of that ledger, and the margin effect is larger than most finance teams expect. Executive summary Caribbean retailers and manufacturers are no longer simply buyers and sellers of goods. They...

Canada’s Reversal and the Uncertain Road to Pillar One

Canada enacted a digital services tax, reached back two years to collect it, then repealed it and refunded the money with interest. The episode is a lesson in legislative risk, and a signpost for Caribbean states choosing between the OECD, the United Nations and their own consumption taxes. Executive summary In June 2024 Canada enacted...

Who Collects Tax When a Platform Sits in the Middle

Marketplaces, booking sites and delivery apps now stand between Caribbean sellers and their customers. The law increasingly decides who collects the tax by who controls the transaction, not by who owns the product. Sellers who assume “the platform handles it” are carrying risk they have not measured. Executive summary A single online sale can involve...

The Caribbean Digital Tax Moment

Jamaica’s Budget, Grenada’s new law and years of quiet collection in Barbados and The Bahamas mean digital tax is no longer a foreign debate. It is a Caribbean compliance question, and boards need a method to answer it. Executive summary Until recently, “digital tax” in the Caribbean meant headlines from Paris, London and Ottawa. In...

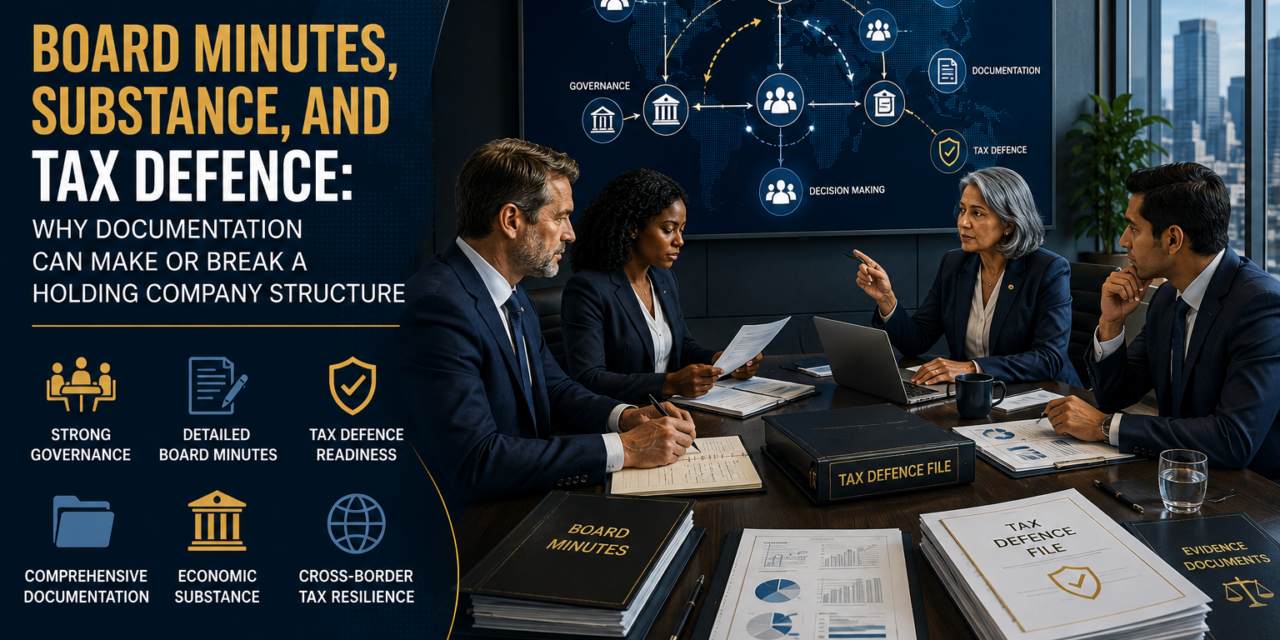
Board Minutes and Tax Substance: Why Documentation Can Make or Break a Holding Company Structure

  Executive Summary In modern international tax planning, documentation is no longer an administrative afterthought. It is a central part of tax defence. Holding companies, investment platforms, regional headquarters, and cross-border ownership structures may be legally valid, but they remain exposed if the evidence does not prove that they are commercially real. The recent Milan...

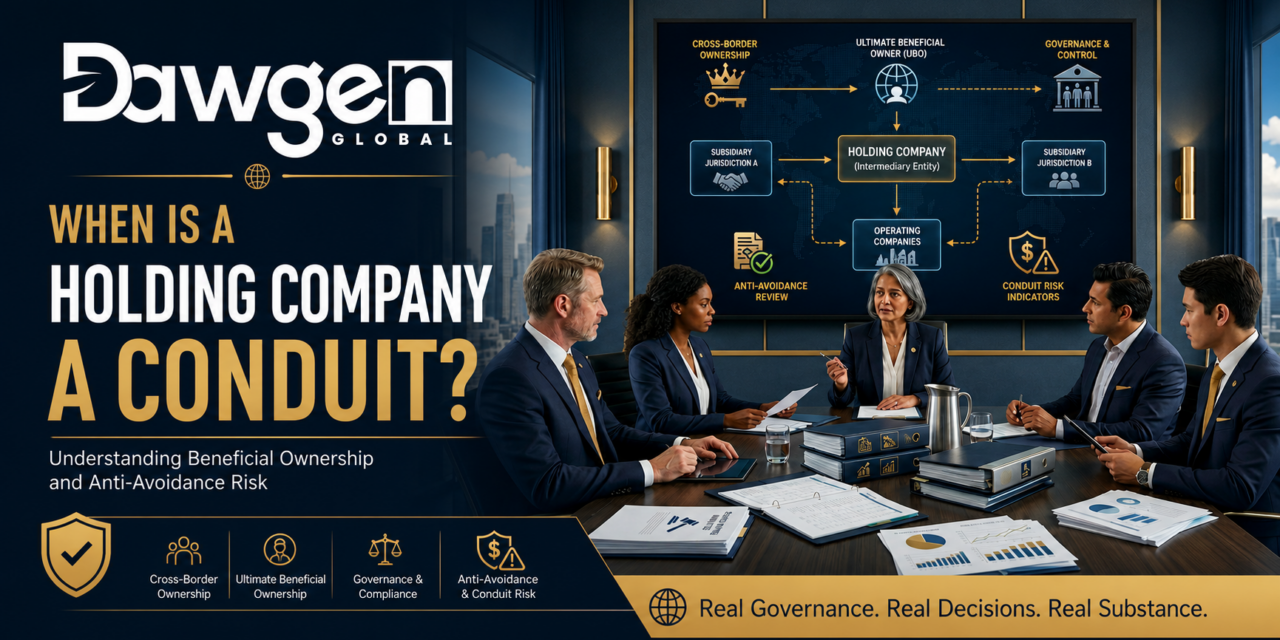
When Is a Holding Company a Conduit? Understanding Beneficial Ownership and Anti-Avoidance Risk

Key Insight: A holding company is not vulnerable merely because it is lean. It becomes vulnerable when it lacks real substance, decision-making autonomy, commercial purpose, and evidence that it controls the income or assets it legally holds. Executive Summary Holding companies remain valuable tools in international tax and corporate structuring. They can support investment management,...

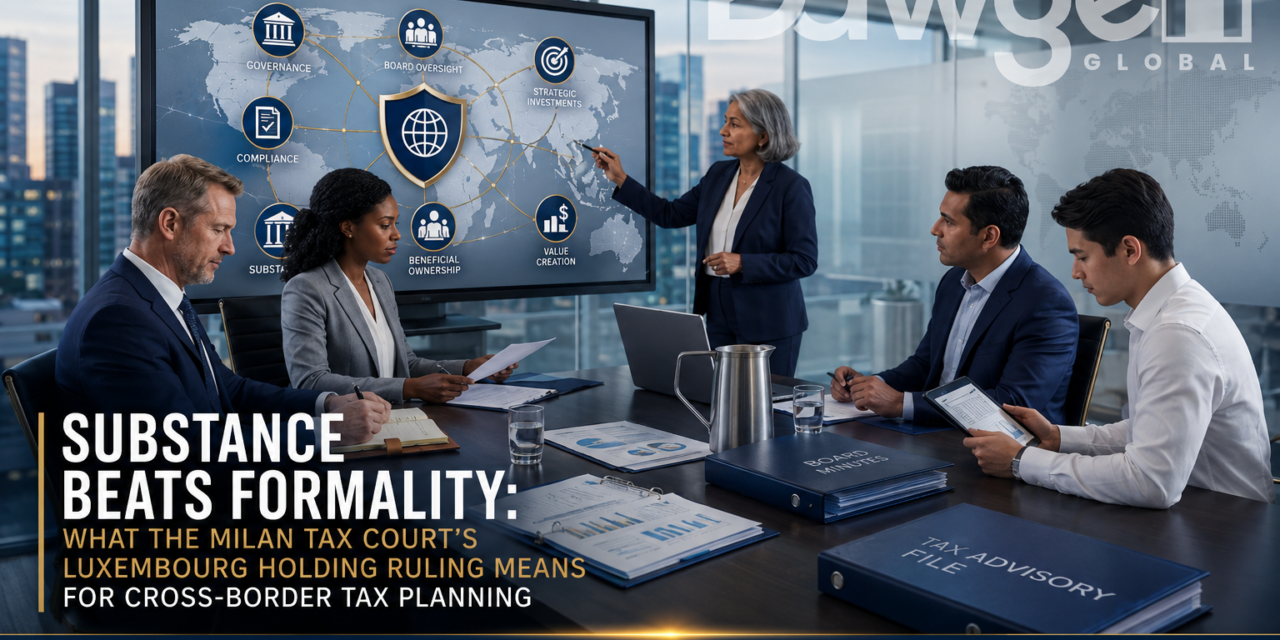
Substance Beats Formality: What the Milan Tax Court’s Luxembourg Holding Ruling Means for Cross-Border Tax Planning

  Executive Summary International tax planning is entering a new era in which paper structures are no longer sufficient, but genuine commercial substance remains powerful. A recent ruling by the First Instance Tax Court of Milan provides an important reminder that foreign holding companies should not automatically be disregarded simply because they are lean, investment-focused...

https://www.dawgen.global/wp-content/uploads/2023/07/Foo-WLogo.png

Dawgen Global is an integrated multidisciplinary professional service firm in the Caribbean Region. We are integrated as one Regional firm and provide several professional services including: audit, accounting, tax, IT, risk, HR, performance, M&A, corporate recovery and other advisory services

Where to find us?
https://www.dawgen.global/wp-content/uploads/2019/04/img-footer-map.png
Dawgen Social links

© 2026 Copyright Dawgen Global. All rights reserved.  ·  Privacy Notice  ·  Cookie Policy  ·  Website Terms  ·  Accessibility