Retailers and manufacturers now buy software, advertising and cloud capacity from abroad and sell through websites, marketplaces and chat apps. Digital tax reaches both sides of that ledger, and the margin effect is larger than most finance teams expect.
Executive summary
Caribbean retailers and manufacturers are no longer simply buyers and sellers of goods. They run cloud enterprise resource planning (ERP) systems, pay foreign platforms for advertising, subscribe to software as a service (SaaS), sell through their own websites, regional marketplaces and WhatsApp catalogues, and increasingly attach services such as remote monitoring, subscriptions and extended warranties to the products they make. Each of those flows has its own tax character.
On the cost side, Jamaica already requires registered businesses to self-account for General Consumption Tax (GCT) on imported services under section 23B of the GCT Act, and payments to non-residents for royalties or fees can attract withholding tax at 33⅓ per cent, or 15 per cent under the Caribbean Community (CARICOM) Double Taxation Agreement. On the revenue side, goods sold online remain goods: Trinidad and Tobago’s 7 per cent Online Purchase Tax reaches imported goods, not services, while Barbados, The Bahamas and Suriname tax foreign digital services to their consumers. Jamaica’s proposed GCT on digital services from abroad, planned for January–March 2027, adds a further layer.
Below: a channel matrix, an illustrative margin calculation and the case for treating every ERP migration as a tax event.
Two ledgers, one tax map
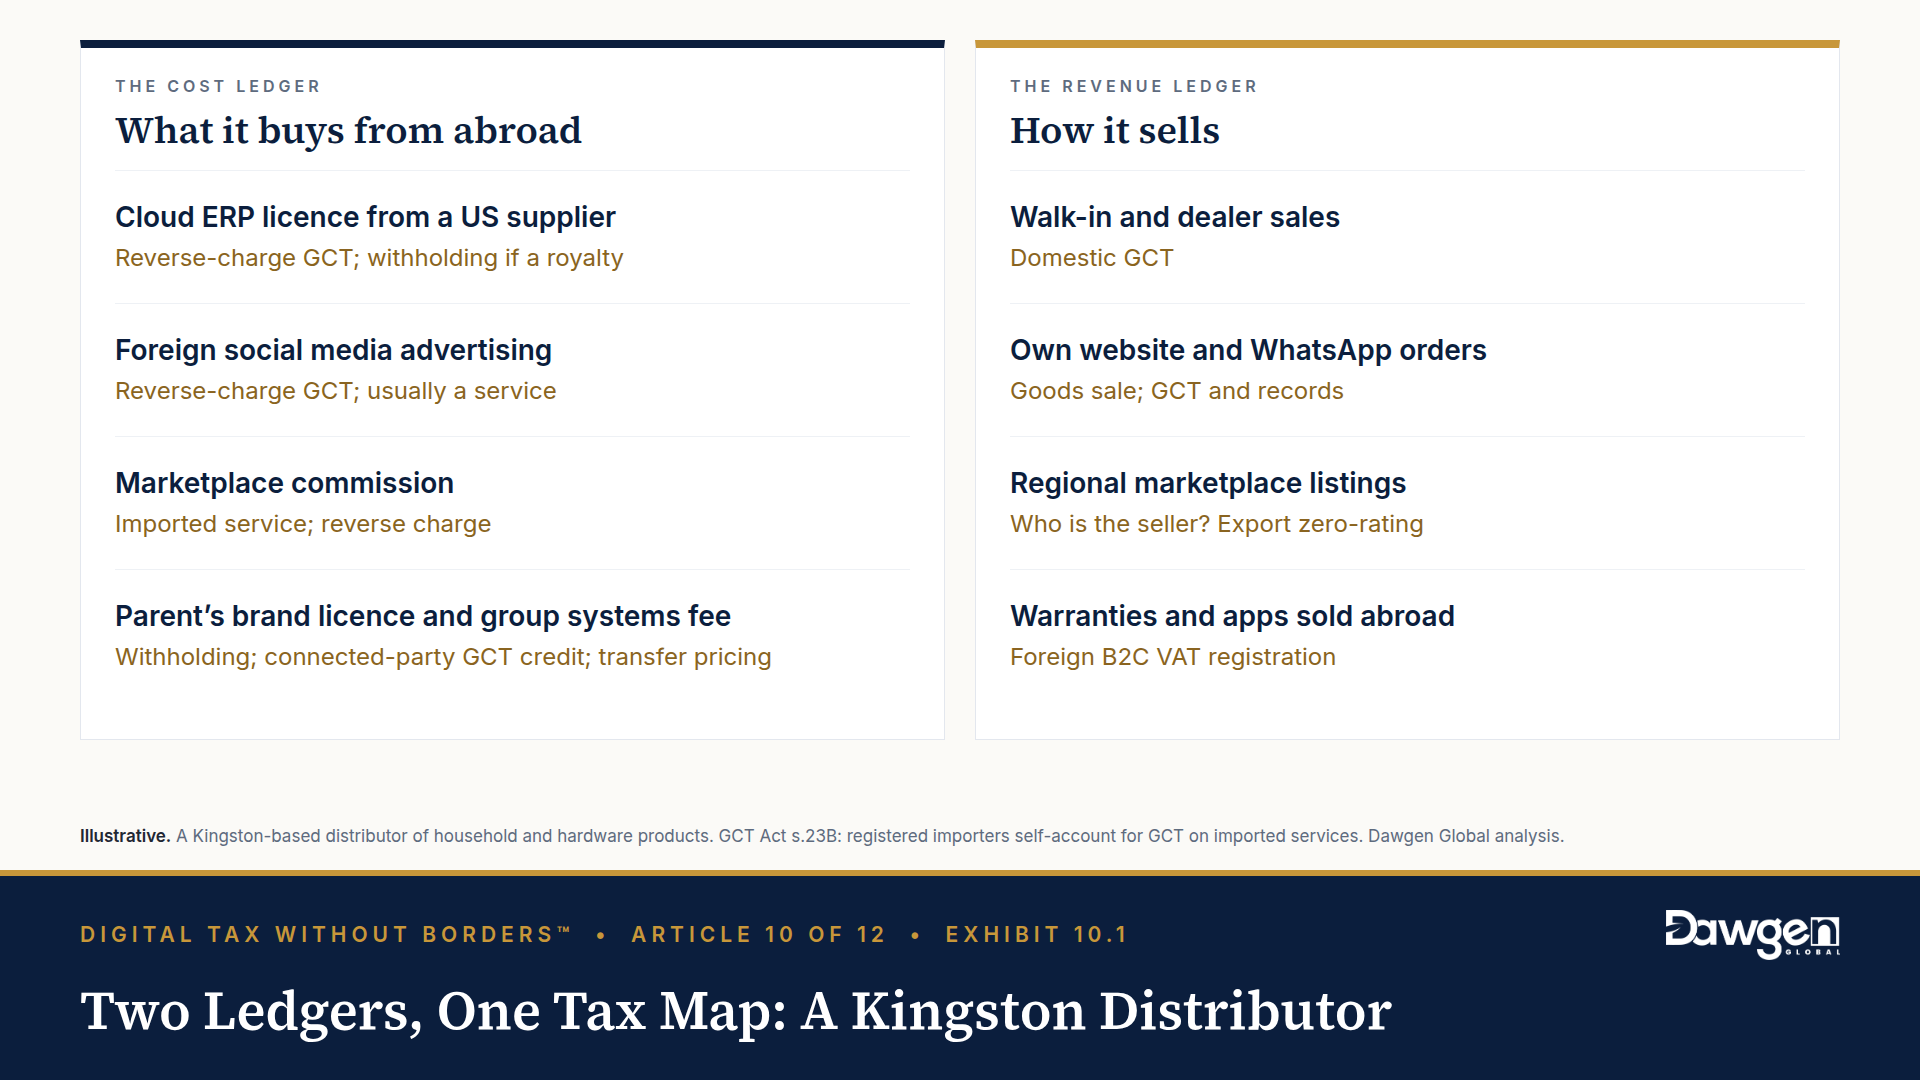
The traditional merchant tax file is built around the physical product: customs duty and import GCT or value added tax (VAT) at the port, output tax on domestic sales, zero-rating on exports. What has changed is that a growing share of costs, and a rising share of revenue, is now digital, and digital flows follow different rules.
Consider a Kingston-based distributor of household and hardware products. It imports inventory by sea, sells to walk-in customers and dealers, runs its own website, lists selected lines on a regional marketplace, takes orders through a WhatsApp Business catalogue and pays a foreign social media platform for advertising. Its warehouse and accounts run on a cloud ERP licensed from a United States supplier, and its parent in Trinidad and Tobago charges a monthly fee for group systems and a licence to use the brand. That one business faces at least six distinct tax questions, and the cost-side answers matter as much as the revenue-side ones.
Law in force vs proposal. In force today in Jamaica: GCT on imported services, self-accounted by registered importers (GCT Act s.3(1)(b) and s.23B), and withholding tax on royalties and fees paid to non-residents. Proposed, not yet enacted: GCT on digital services and intangibles supplied from abroad and consumed in Jamaica, announced in the 2026/27 Budget for implementation in the fourth quarter of fiscal year (FY) 2026/27. As far as public sources show, enabling legislation and Tax Administration Jamaica (TAJ) guidance had not been published by late September 2026.
The cost side: imported digital services
The reverse charge is already the law
Many Jamaican finance teams treat the 2026/27 Budget as the moment digital purchases enter the GCT net [1][2][3]. For registered businesses, that moment passed long ago. Section 23B of the GCT Act, introduced in 2003 and made operational through the Provisional Collection of Tax (GCT) (No. 5) Order 2014, requires a registered taxpayer that imports a service to account for GCT on it as if it had made the supply itself; the TAJ Technical Bulletin of April 2020 sets out the mechanics [4]. The importer declares output tax and, where the conditions are met, claims the same amount as input tax.
For a fully taxable retailer buying from an unconnected supplier, the result is cash-neutral but not risk-neutral: failing to self-account is an under-declaration. More importantly, input credit on imported services from connected parties is restricted, subject to market value and supplier capacity conditions [4]. A group recharge from a regional parent can therefore carry GCT that becomes a real cost.
The proposed measure matters most to businesses below the J$15 million registration threshold in force from 1 April 2025 [16]. Small retailers and micro-manufacturers that subscribe to point-of-sale software, design tools or advertising sit outside the reverse charge today. If foreign suppliers are required to charge 15 per cent GCT, those businesses will bear it as an unrecoverable cost. Of the projected J$4.2 billion a year from FY2027/28 [1][2], part will fall on small and medium-sized enterprises (SMEs) buying business tools.
Withholding tax is the bigger number
Reverse-charged GCT is usually recoverable; withholding under a gross-up clause is the payer’s cost. Jamaica imposes withholding at 33⅓ per cent on royalties and on management and service fees paid to non-residents [5]. The CARICOM Double Taxation Agreement of 1994 limits source-state tax on royalties (Article 13) and management fees (Article 14) to 15 per cent of the gross amount for residents of participating states [6]; treaties with the United States and Canada can reduce rates further [5].
Whether a digital payment is a royalty, a fee or a service outside withholding depends on what is supplied. A licence to use software or a brand looks like a royalty; hosting capacity or an advertising placement is more naturally a service. A cloud ERP contract usually combines access, implementation, training and support, and each component drives its own result.
Illustrative example: a Kingston distributor’s online channel
The figures are illustrative only and do not represent any actual business. The distributor’s online channel generates J$120 million a year of sales, net of GCT. At a 25 per cent gross margin, product margin is J$30 million. After marketplace commission of J$9.6 million, foreign advertising of J$6.4 million and fulfilment of J$6 million, channel contribution is J$8 million before overheads. The channel’s share of the cloud ERP licence is J$9.6 million a year, paid to a non-resident under a contract that forbids any deduction for tax. Assume the licence is characterised as a royalty.
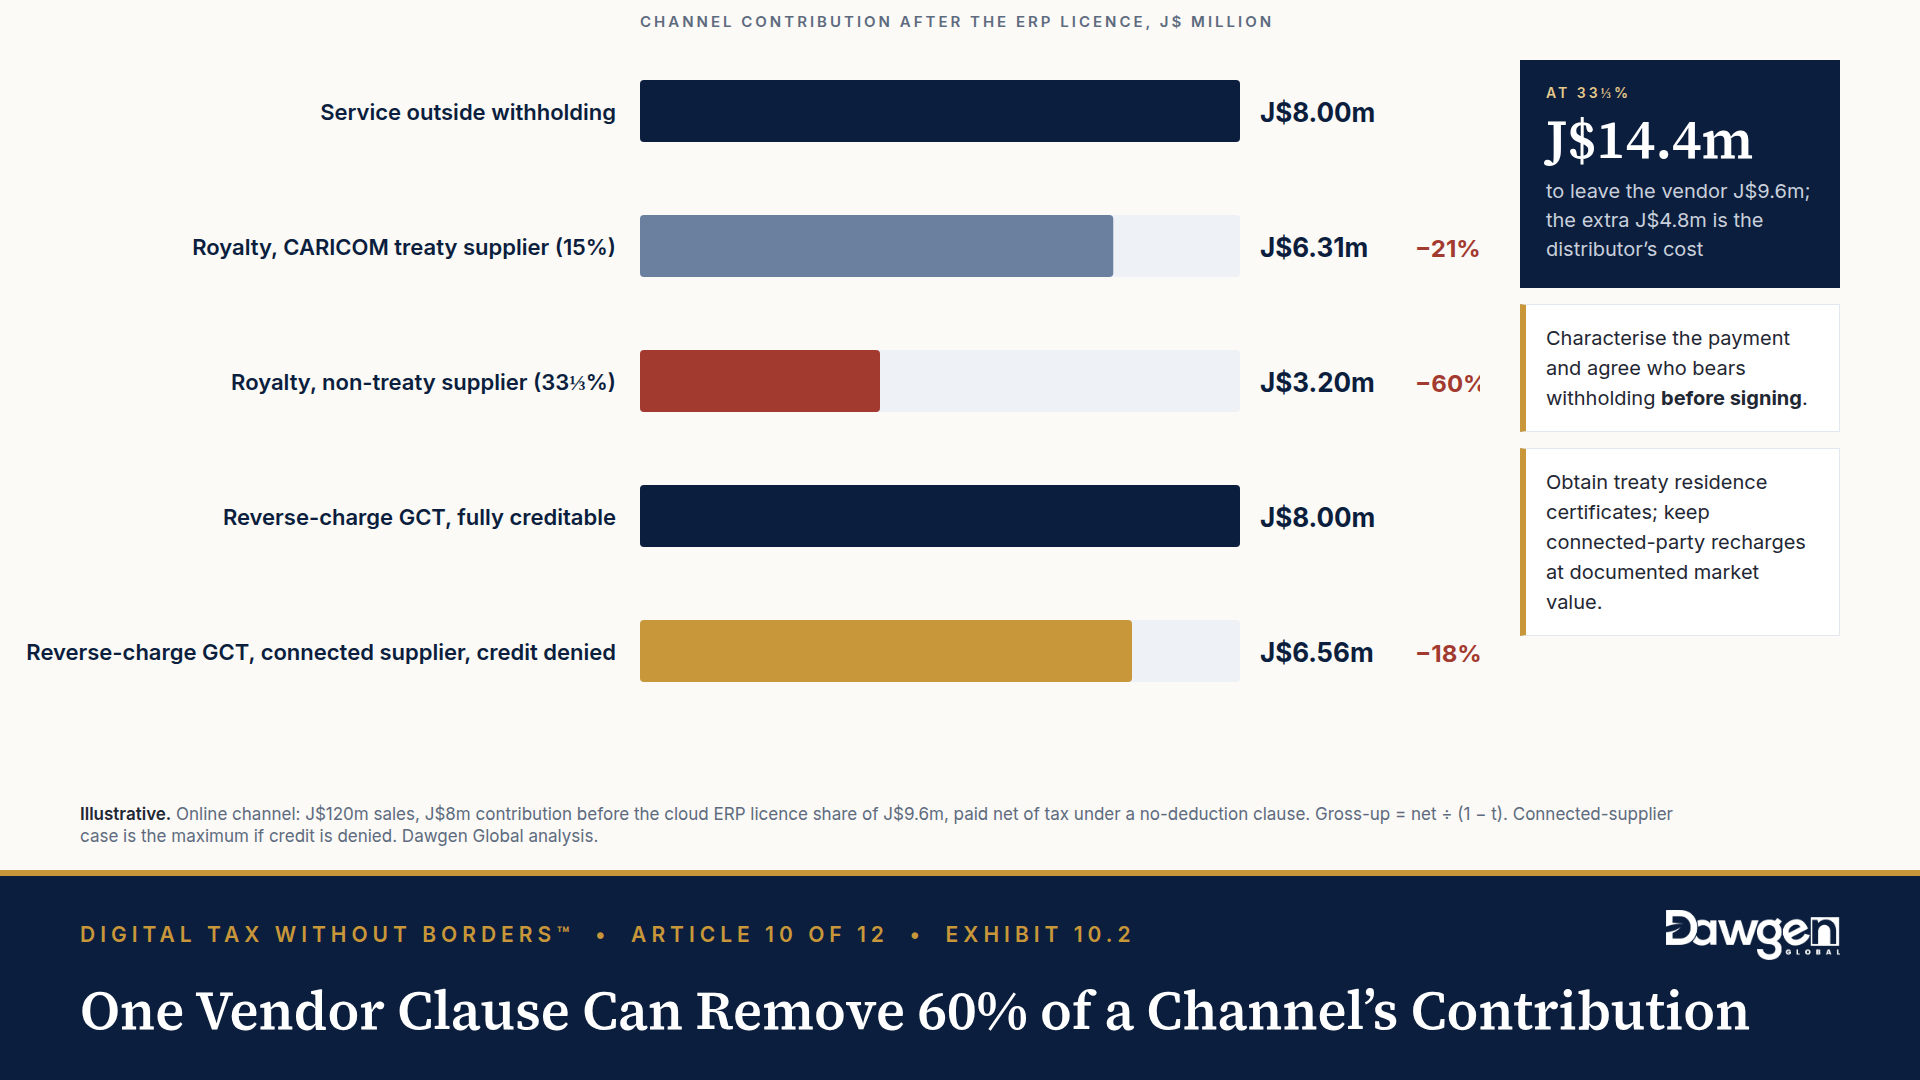
Where the payer bears withholding at rate t, the gross payment is the net amount divided by (1 – t); at 33⅓ per cent, J$9.6 million becomes J$14.4 million. One vendor clause can remove more than half a channel’s contribution. Characterise the payment and negotiate who bears withholding before signing, route foreign digital contracts through tax review, obtain treaty residence certificates, and keep connected-party recharges at documented market value.
The revenue side: selling goods and services across the region
A goods sale ordered online is still a goods sale
A kettle sold through a website is not a digital service. The Organisation for Economic Co-operation and Development (OECD) International VAT/GST Guidelines, which underpin the destination principle used across the region, address services and intangibles; goods remain taxed on import and on domestic supply [14]. The OECD, World Bank, Inter-American Center of Tax Administrations (CIAT) and Inter-American Development Bank (IDB) VAT Digital Toolkit for Latin America and the Caribbean draws the same line [15].
The distinction bites when goods cross borders. Trinidad and Tobago has no specific VAT regime for foreign digital services, but it imposes a 7 per cent Online Purchase Tax on goods bought online and imported by air; its standard VAT rate is 12.5 per cent [7]. A Kingston retailer air-freighting orders to consumers in Port of Spain should expect those customers to meet the Online Purchase Tax on importation. The tax does not reach services. Trinidad and Tobago’s FY2026 Budget signalled a review of the VAT system [17], so the position needs watching.
Digital add-ons follow the services rules
Once a business sells something other than the physical product — an online extended warranty, an app subscription, a design service, remote equipment monitoring — it is supplying a service or intangible, and several jurisdictions already tax such supplies from abroad to their consumers. Barbados applies VAT at 17.5 per cent to digital services from foreign suppliers, with registration through the Barbados Revenue Authority’s TAMIS portal, since 1 December 2019 [8]. The Bahamas charges VAT at 10 per cent on electronic commerce services supplied to persons in The Bahamas and requires non-resident suppliers to register [9]. Suriname has taxed foreign business-to-consumer (B2C) electronic services at 10 per cent since 1 January 2023 [10]. Grenada’s VAT (Amendment) Bill 2026, passed on 7 May 2026 and awaiting commencement, will require non-resident suppliers to register for B2C supplies and apply a reverse charge to business-to-business (B2B) supplies [11]. Guyana requires recipients to self-account for VAT at 14 per cent on imported services [12].
Remote monitoring sold to hotels in The Bahamas is usually a B2B supply governed by the customer’s rules; a warranty plan sold to Barbadian households makes the manufacturer a foreign digital supplier that must assess registration. There is no harmonised regime: when CARICOM and the Caribbean Organisation of Tax Administrators (COTA) co-hosted a regional VAT workshop on 4 March 2026, officials from 13 countries discussed cross-border digital transactions, but no model law has emerged [13].
Marketplaces and social commerce
On a regional marketplace, the first question is who the legal seller is. If the platform buys and resells, the merchant’s customer is the platform. If it acts as agent, the merchant sells to the consumer and buys an intermediation service, which is a reverse-charged import where the platform is foreign. The monthly settlement, which nets sales, refunds and fees, must be reconciled to gross sales rather than booked as one net receipt.
WhatsApp and Instagram commerce has no settlement statement at all: orders arrive in chat and payment by transfer or link. The tax is that of a counter sale, but the evidence trail is thin, so material social channels need order numbers, invoices and customer location captured at the point of sale.
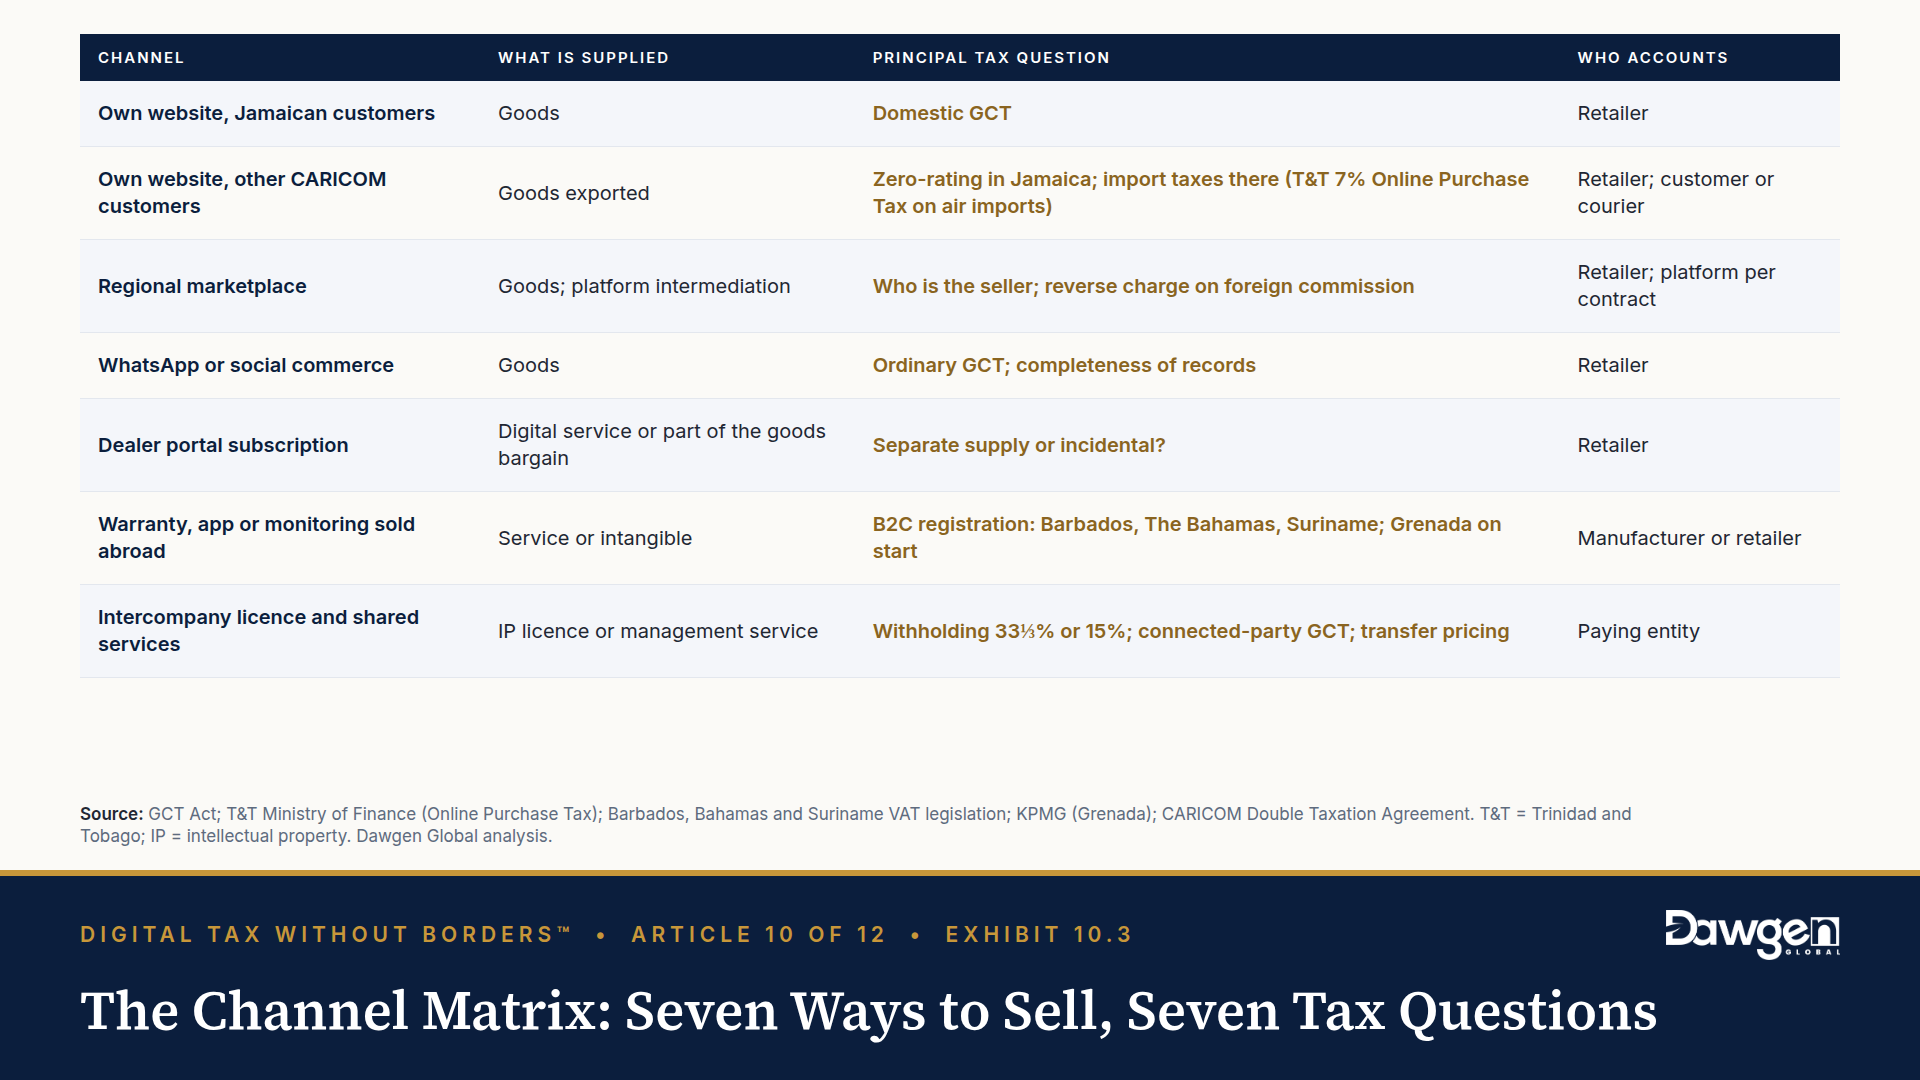
Channel matrix
Regional distribution and intercompany charges
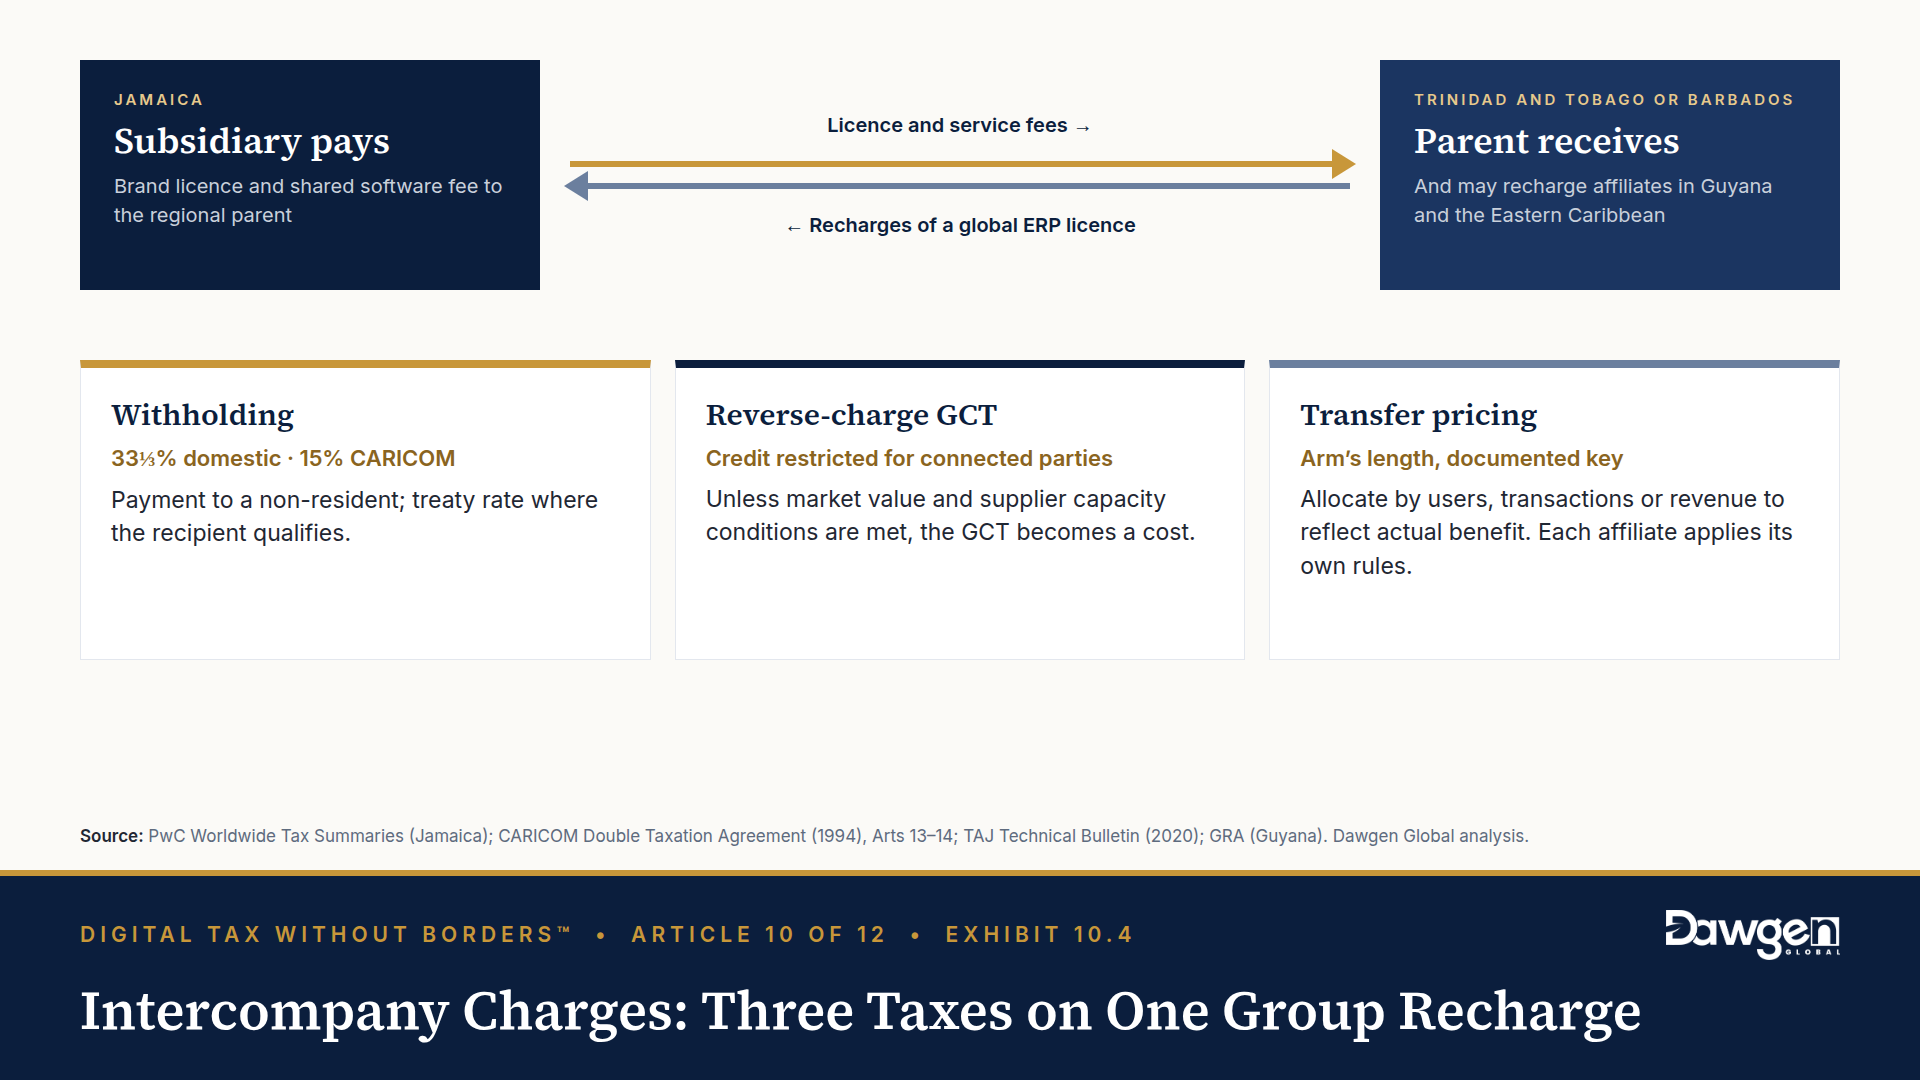
When a Jamaican subsidiary pays a Trinidadian or Barbadian parent for a brand licence or shared software, it is paying a non-resident. Withholding applies, reduced to 15 per cent under the CARICOM agreement where the recipient qualifies [6]. The service element is an imported service for GCT, and because the parties are connected, input credit is restricted unless the market value and capacity conditions are met [4]. The charge must also be priced at arm’s length, using an allocation key — users, transactions or revenue — that reflects actual benefit.
The reverse flow matters equally. A Jamaican head office that buys a global cloud ERP licence and recharges affiliates in Barbados, Guyana and the Eastern Caribbean does not discharge their local obligations by paying the foreign invoice. Each affiliate receives a service from Jamaica and must apply its own import VAT and withholding rules; Guyana’s self-accounting requirement is one example [12].
Each tax has its own nexus test: a Barbados VAT registration does not create a permanent establishment (PE) for income tax, while sales staff or a warehouse in another island may create one without any VAT registration.
Manufacturers that sell services
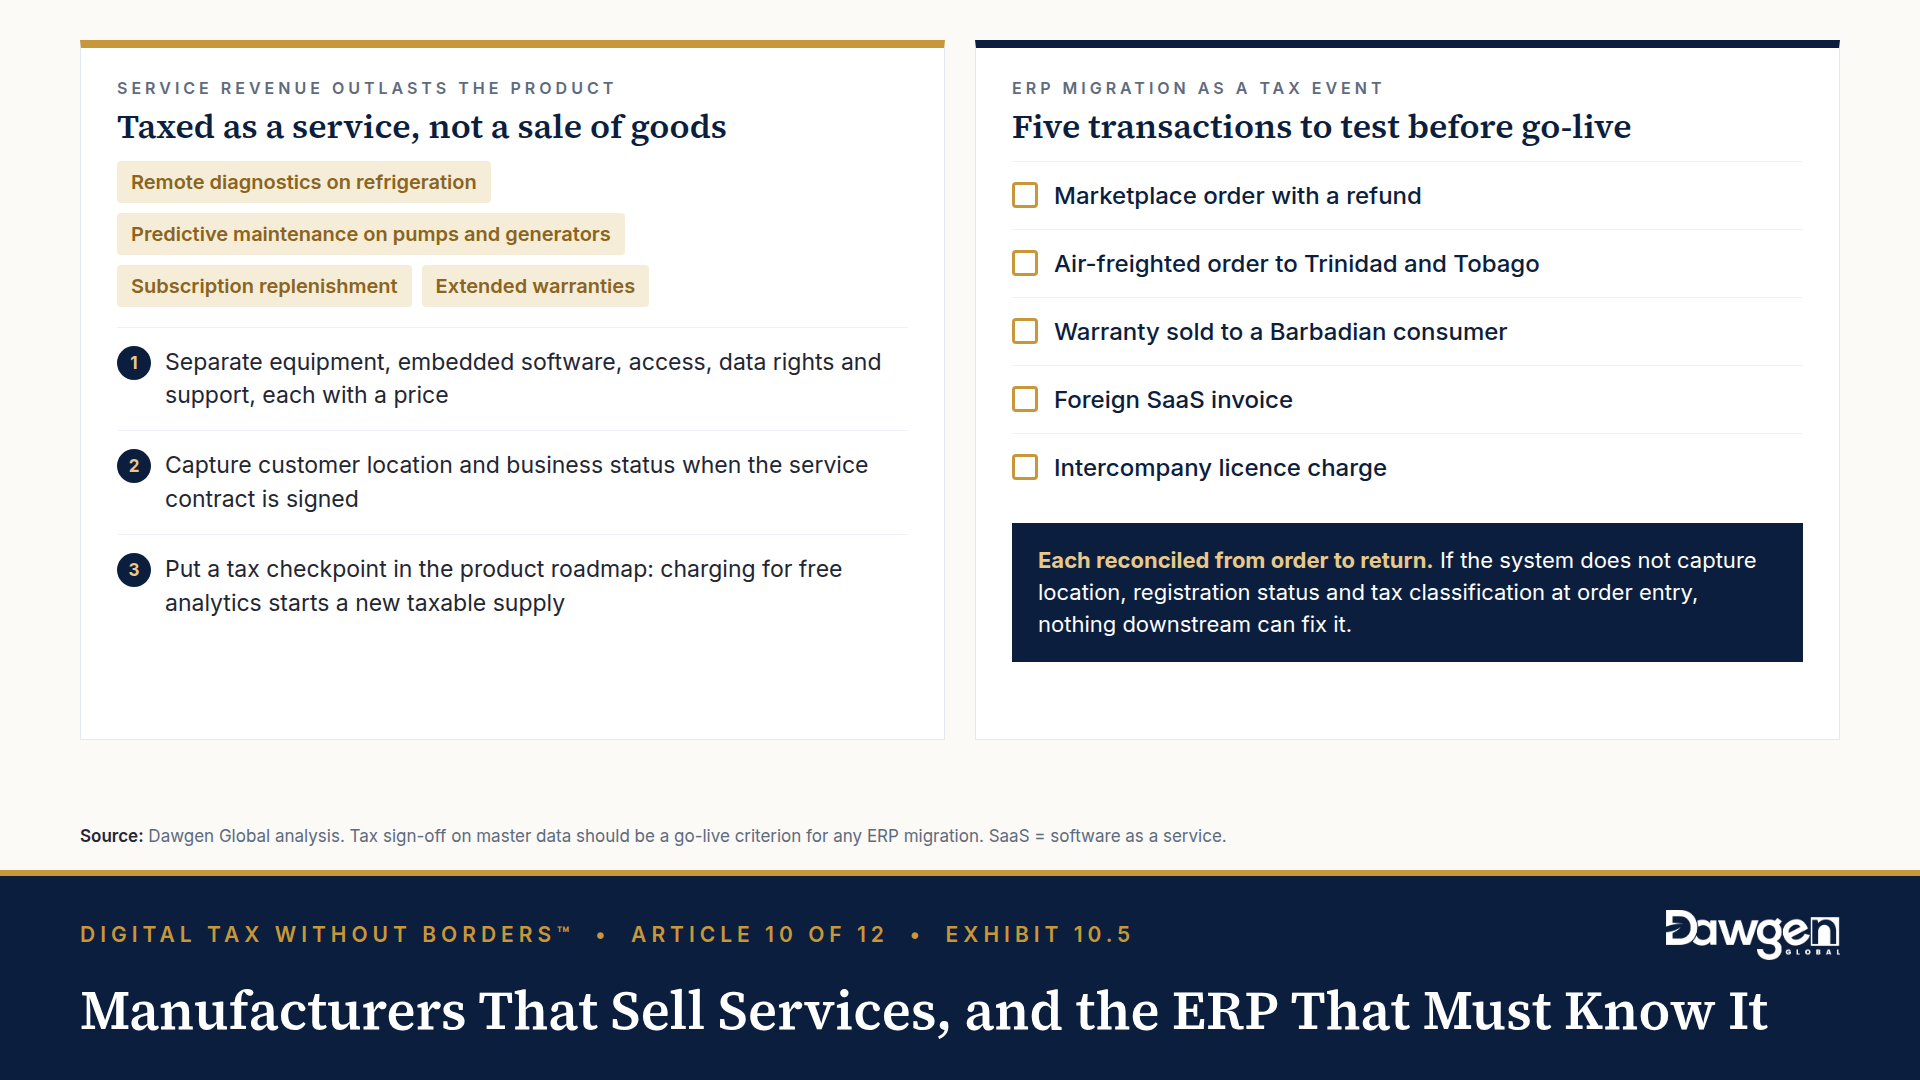
Caribbean manufacturers increasingly sell services alongside products: remote diagnostics on refrigeration, predictive maintenance on pumps and generators, subscription replenishment and extended warranties. That revenue outlasts the physical sale by years, and it is taxed as a service.
Three disciplines follow. The contract must separate equipment, embedded software, ongoing access, data rights and support, with a price or allocation for each; a single bundled price leaves the answer to the default rules of the customer’s jurisdiction. Customer location and business status must be captured when the service contract is signed. And the product roadmap needs a tax checkpoint: the day a manufacturer starts charging for analytics that were free is the day a new taxable supply begins, potentially in several jurisdictions. Moving from a perpetual software licence to a cloud subscription can also shift the payment from royalty towards service in the customer’s country, changing who bears withholding.
ERP migration as a tax event
An ERP migration is the most consequential digital tax decision many merchants will make this decade, and it is rarely treated as one. On procurement, a cloud ERP contract combines subscription, implementation consulting, data migration, local integration partners, training and support. Each component may carry a different GCT and withholding result and should be invoiced to the entity that receives it.
On design, the system fixes what data the business will hold for years. If it does not capture customer location, registration status and product tax classification at order entry, the group cannot evidence export zero-rating, comply with the Barbados, Bahamas or Suriname rules on digital add-ons, or respond when Jamaica’s measure commences. Tax codes should distinguish reverse-charged imports, connected-party imports and withholding.
Before go-live, test a marketplace order with a refund, an air-freighted order to Trinidad and Tobago, a warranty sold to a Barbadian consumer, a foreign SaaS invoice and an intercompany licence charge, each reconciled from order to return. Tax sign-off on master data should be a go-live criterion.
The Dawgen Digital Tax COMPASS™
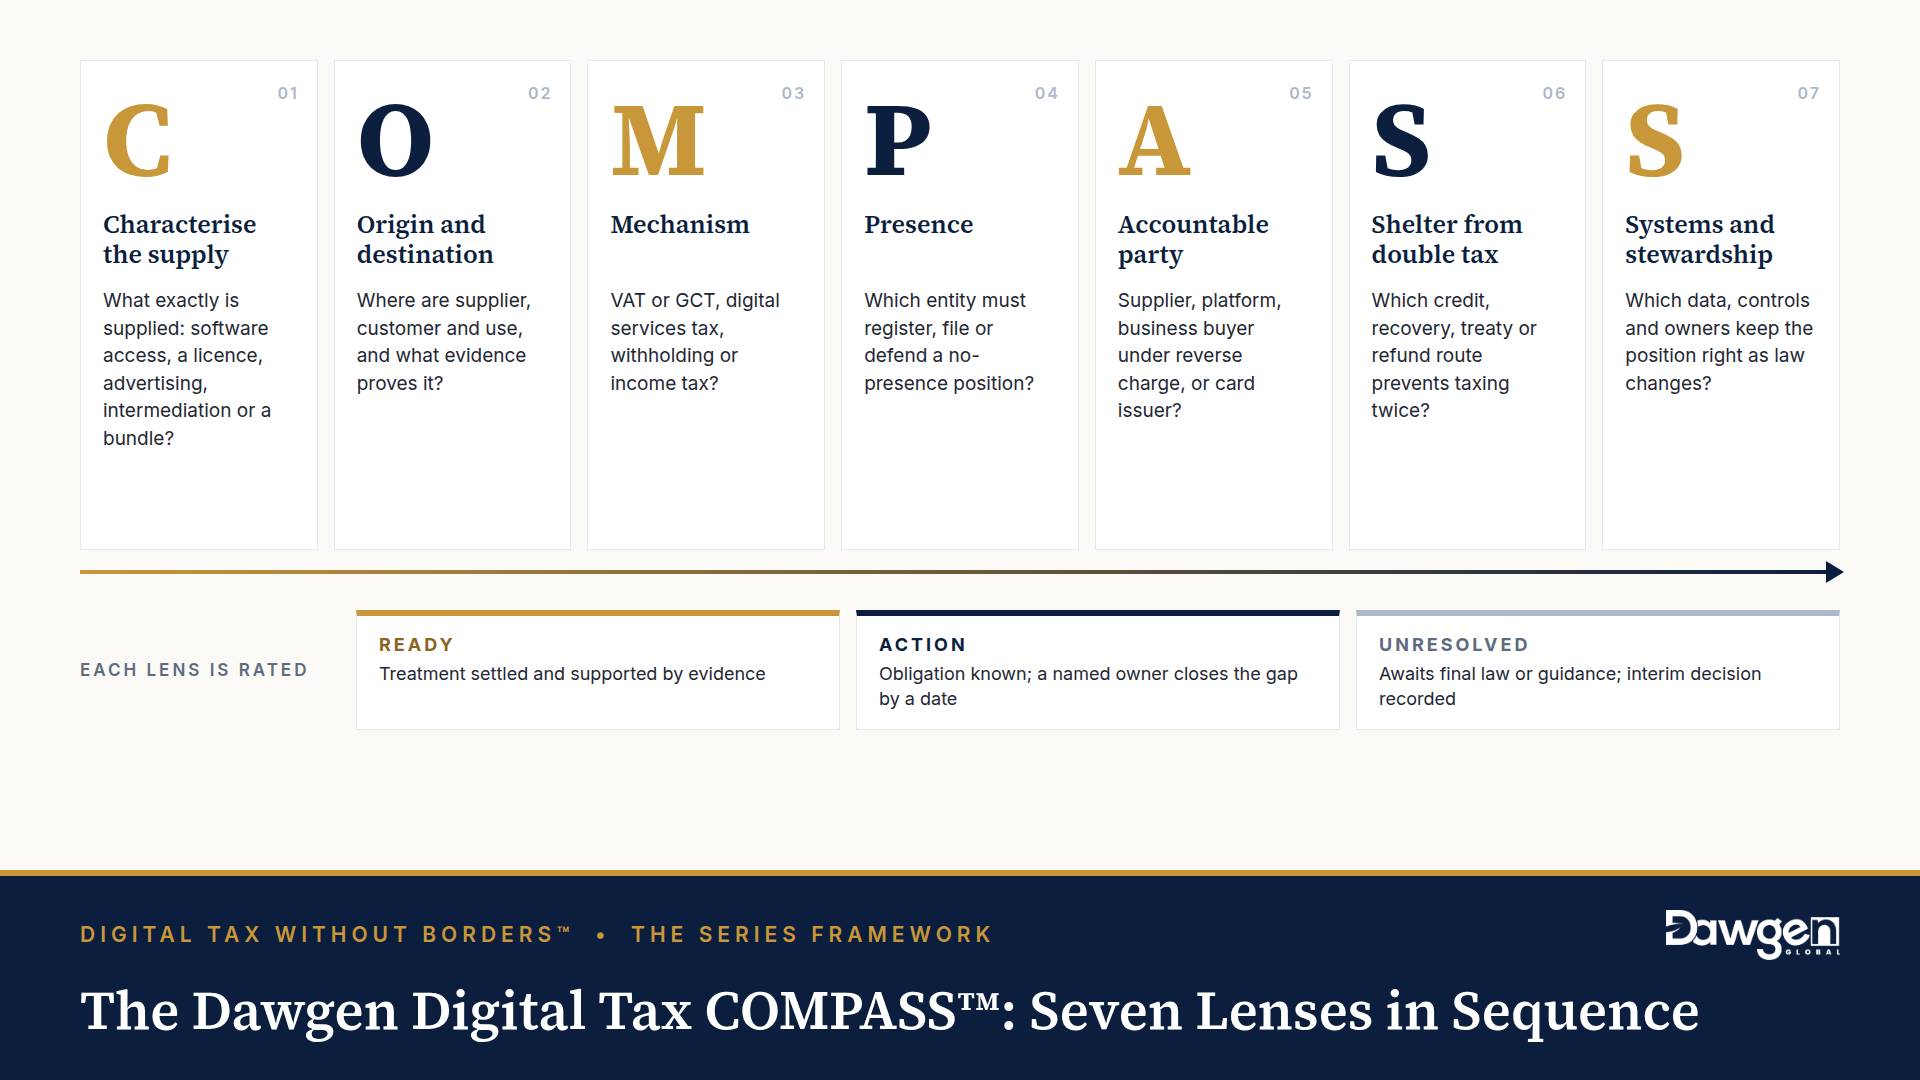
The Dawgen Digital Tax COMPASS™ is the method Dawgen Global uses to turn the broad phrase “digital tax” into specific, answerable questions. It works transaction by transaction, and it applies equally to what a business buys and what it sells. Seven lenses are applied in sequence, because each answer depends on the one before it.
- C — Characterise the supply. What exactly is supplied: access to software, a licence of intellectual property, advertising, intermediation, a professional service delivered remotely, or a bundle of several? The contract and the actual performance decide, not the invoice description.
- O — Origin and destination. Where are the supplier, the customer and the place of use or consumption, and what evidence proves it? Billing address, card country, IP address and contract terms often disagree.
- M — Mechanism. Which tax is in play: VAT or GCT on consumption, a gross-revenue digital services tax, withholding tax on the payment, or income tax on profits? Each has a different taxpayer, base and remedy.
- P — Presence. Which entity has a taxable connection with which jurisdiction, and must it register, file or defend a no-presence position?
- A — Accountable party. Who must actually charge, collect or remit: the supplier, a platform deemed to be the supplier, the business customer under a reverse charge, or a payment intermediary?
- S — Shelter from double taxation. Which credit, input tax recovery, treaty provision or refund route prevents the same value being taxed twice, and is it documented?
- S — Systems and stewardship. Which data fields, controls, owners and monitoring routines keep the position right as volumes grow and the law changes?
Each lens is rated on a simple three-tier scale. Ready means the treatment is settled and supported by evidence. Action means the obligation is known and a named owner is fixing a gap by a date. Unresolved means the answer depends on law or guidance that is not yet final, and an interim commercial decision has been recorded. The output is a transaction-level exposure map and an action plan with owners, not a list of countries. The COMPASS™ identifies and prioritises the questions; each material conclusion is then supported by the law of the jurisdiction concerned.
Applying the COMPASS™ to retail and manufacturing
| Lens | What to ask in this context | Evidence to hold |
| Characterise | Is this a goods sale, a digital add-on, a software licence, an advertising service or a bundle? Is the ERP payment a royalty or a service fee? | Contracts split by component; product master with tax classification |
| Origin and destination | Where are the goods delivered and where is the digital add-on used? Is the foreign vendor resident in a CARICOM treaty state? | Shipping records; customer location indicators; supplier residence certificates |
| Mechanism | Is the exposure import VAT, the 7% Online Purchase Tax, reverse-charge GCT, foreign VAT on B2C services or withholding? | Transaction map showing each tax separately |
| Presence | Do regional sales staff, warehouses or B2C digital sales create registration or PE in another state? | Entity and activity map by jurisdiction |
| Accountable party | Is the retailer, the marketplace, the courier, the customer or the vendor responsible for each tax? | Platform terms; courier arrangements; reverse-charge workings |
| Shelter | Is reverse-charged GCT creditable, restricted for connected parties, or a cost? Is CARICOM treaty relief claimed on royalties? | Input tax workings; treaty forms; withholding certificates |
| Systems and stewardship | Does the ERP capture location, business status and tax code at order entry, and does procurement flag foreign digital contracts? | ERP test log; procurement tax checklist; monthly marketplace reconciliation |
Questions for the board
- What is the after-tax contribution of each sales channel, and how much of the gap between online growth and profit growth is fees and tax?
- Are we self-accounting for GCT under section 23B on every imported service, including card-paid subscriptions?
- Which foreign software, licence and brand payments are royalties, and who bears the withholding under each contract?
- Do our intercompany charges have written agreements, arm’s-length support and treaty residence documentation?
- How much connected-party imported service GCT is irrecoverable, and is it priced into group recharges?
- Which services or digital add-ons do we sell to consumers in Barbados, The Bahamas, Suriname or Grenada?
- Will our next ERP release capture the data needed for Jamaica’s proposed measure and for export evidence?
- What will the proposed digital GCT cost our unregistered entities, and which contracts let vendors add it?
How Dawgen Global can help
Dawgen Global’s Caribbean Tax Advisory practice helps boards, finance leaders and owner-managers of retail and manufacturing businesses understand how digital tax affects their channels, suppliers and intercompany arrangements. Using the Dawgen Digital Tax COMPASS™, we map digital transactions across the jurisdictions in which you operate, separate law in force from proposals, quantify exposure and help your team put in place the contracts, systems and controls to stay compliant as the rules change. To discuss your organisation’s position, contact us at [email protected] or visit www.dawgen.global/contact-us.
This is the tenth article in the Digital Tax Without Borders™ series.
This article provides general information and does not constitute tax or legal advice. The application of tax law depends on specific facts and on the law in force at the relevant date; readers should obtain advice before acting.
Abbreviations used
- B2B — business-to-business
- B2C — business-to-consumer
- CARICOM — Caribbean Community
- CIAT — Inter-American Center of Tax Administrations
- COTA — Caribbean Organisation of Tax Administrators
- ERP — enterprise resource planning
- FY — fiscal year
- GCT — General Consumption Tax
- IDB — Inter-American Development Bank
- IP — intellectual property (in “IP address”, internet protocol)
- OECD — Organisation for Economic Co-operation and Development
- PE — permanent establishment
- SaaS — software as a service
- SMEs — small and medium-sized enterprises
- TAJ — Tax Administration Jamaica
- VAT — value added tax
Sources
- Ministry of Finance and the Public Service (Jamaica), Revenue Measures (including Ministry Paper No. 17, “Revenue Measures for Financial Year 2026/2027”, 12 February 2026, and amended measures, 28 April 2026). https://www.mof.gov.jm/resources-revenue-measures/
- Jamaica Information Service, “Gov’t projects $29.4B from new revenue measures in fiscal year 2026/27”, February 2026. https://jis.gov.jm/govt-projects-29-4b-from-new-revenue-measures-in-fiscal-year-2026-27/
- EY, “Jamaica proposes extending General Consumption Tax to digitally supplied services and intangibles from abroad”, Tax Alert, 25 February 2026. https://www.ey.com/en_gl/technical/tax-alerts/jamaica-proposes-extending-general-consumption-tax-to-digitally-supplied-services-and-intangibles-from-abroad
- Tax Administration Jamaica, Technical Bulletin, “Accounting for GCT on Imported Services”, 23 April 2020. https://www.jamaicatax.gov.jm/documents/10181/17838406/Technical+Bulletin+(2020)+-+GCT+Imported+Services_23042020.pdf/547fce5a-fa9c-1481-ec55-6d8e40456f08
- PwC, Worldwide Tax Summaries, “Jamaica: Corporate — Withholding taxes”, accessed September 2026. https://taxsummaries.pwc.com/jamaica/corporate/withholding-taxes
- Caribbean Community, “Agreement among the Governments of the Member States of the Caribbean Community for the Avoidance of Double Taxation…” (CARICOM Double Taxation Agreement), 1994. https://caricom.org/treaties/double-taxation-agreement/
- Grant Thornton, “Indirect tax guide: Trinidad and Tobago”, accessed September 2026. https://www.grantthornton.global/en/insights/indirect-tax-guide/indirect-tax—Trinidad_and_Tobago/
- PwC, Worldwide Tax Summaries, “Barbados: Corporate — Other taxes”, accessed September 2026. https://taxsummaries.pwc.com/barbados/corporate/other-taxes
- Bahamas Department of Inland Revenue, Value Added Tax Act (consolidated), 2024. https://inlandrevenue.finance.gov.bs/wp-content/uploads/2024/11/Value-Added-Tax-Act.pdf
- VATcalc, “Suriname 10% VAT on foreign digital service providers 2023”. https://www.vatcalc.com/suriname/suriname-10-vat-on-foreign-digital-service-providers-2023/
- KPMG, “Grenada: Nonresident digital services providers subject to VAT”, TaxNewsFlash, May 2026. https://kpmg.com/us/en/taxnewsflash/news/2026/05/grenada-nonresident-digital-services-vat.html
- Guyana Revenue Authority, “VAT Services — Imported Services”, accessed September 2026. https://www.gra.gov.gy/tax-services/vat-services/imported-services/
- Caribbean Community, “Coordinated approach necessary for consistent application of VAT systems — tax officials”, March 2026. https://caricom.org/coordinated-approach-necessary-for-consistent-application-of-vat-systems-tax-officials/
- OECD, International VAT/GST Guidelines, 2017. https://www.oecd.org/en/publications/international-vat-gst-guidelines_9789264271401-en.html
- CIAT, “New toolkit to strengthen value-added taxes on e-commerce in Latin America and the Caribbean” (OECD/World Bank/CIAT/IDB VAT Digital Toolkit), 23 June 2021. https://www.ciat.org/new-toolkit-to-strengthen-value-added-taxes-on-e-commerce-in-latin-america-and-the-caribbean/?lang=en
- PwC, Worldwide Tax Summaries, “Jamaica: Corporate — Other taxes”, accessed September 2026. https://taxsummaries.pwc.com/jamaica/corporate/other-taxes
- Ministry of Finance (Trinidad and Tobago), Budget Statement Fiscal Year 2026, October 2025. https://www.finance.gov.tt/wp-content/uploads/2025/10/Budget-Statement-FY-2026-2.pdf
About Dawgen Global
Dawgen Global is an independent, integrated multidisciplinary professional services firm headquartered at 47 Trinidad Terrace, New Kingston, Jamaica, serving more than 15 territories across the Caribbean. Founded and led by Dr. Dawkins Brown, Executive Chairman, the firm is independent and not affiliated with any international network. It delivers a full suite of professional services under one roof: audit and assurance; tax advisory; IT and digital transformation; risk management; cybersecurity; actuarial and insurance regulatory advisory; HR advisory; mergers and acquisitions; corporate recovery; business advisory and strategy; accounting BPO and virtual CFO services; and legal process outsourcing.
The proposition is simple: big-firm capability without the big-firm price. Dawgen Global’s integrated approach is built for the specific complexities and opportunities of the Caribbean market, helping organizations make sharper, better-informed decisions that drive measurable progress.
To explore a partnership, reach out:
- Website: dawgen.global
- Email: [email protected]
- WhatsApp (Global): +1 555-795-9071
- Caribbean offices: +1 876-665-5926 | +1 876-929-3670 | +1 876-926-5210