HomeCategory

IT & Digital Transformation

The Vanishing Base: When AI and Automation Erode the Foundation of Professional Firms

  Technology is not coming for the apex first. It is dissolving the base — and how a base disappears determines whether a firm becomes a diamond or an hourglass. ISOLATE & AUGMENT · THE SECOND AND THIRD DIMENSIONS Disruption from the bottom up There is a comforting story that technology comes for the routine...
Leverage Under Pressure: Why the Billable Pyramid Is Stalling

Leverage built the modern firm. Understanding its mathematics is the first step in the DIAMOND™ Framework — and the first step in seeing why it can no longer carry the load.   DIAGNOSE · THE FIRST DIMENSION The most powerful number you rarely discuss Ask a managing partner what drives their profitability and you will...

Board Minutes and Tax Substance: Why Documentation Can Make or Break a Holding Company Structure

  Executive Summary In modern international tax planning, documentation is no longer an administrative afterthought. It is a central part of tax defence. Holding companies, investment platforms, regional headquarters, and cross-border ownership structures may be legally valid, but they remain exposed if the evidence does not prove that they are commercially real. The recent Milan...

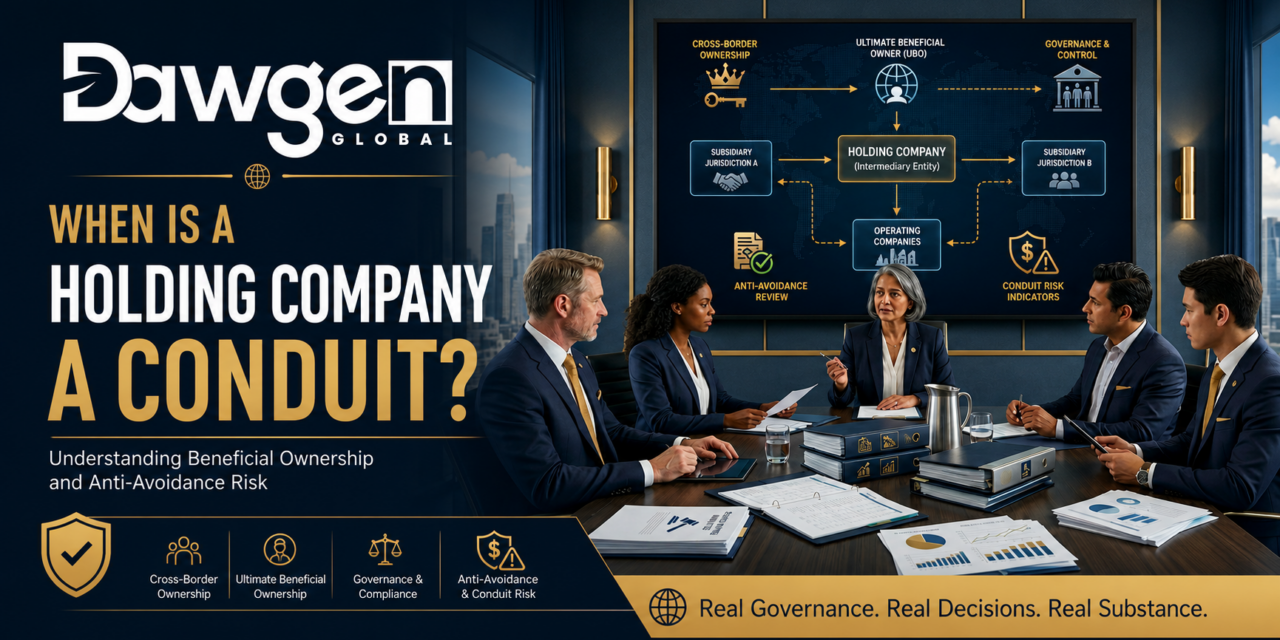
When Is a Holding Company a Conduit? Understanding Beneficial Ownership and Anti-Avoidance Risk

Key Insight: A holding company is not vulnerable merely because it is lean. It becomes vulnerable when it lacks real substance, decision-making autonomy, commercial purpose, and evidence that it controls the income or assets it legally holds. Executive Summary Holding companies remain valuable tools in international tax and corporate structuring. They can support investment management,...

Substance Beats Formality: What the Milan Tax Court’s Luxembourg Holding Ruling Means for Cross-Border Tax Planning

  Executive Summary International tax planning is entering a new era in which paper structures are no longer sufficient, but genuine commercial substance remains powerful. A recent ruling by the First Instance Tax Court of Milan provides an important reminder that foreign holding companies should not automatically be disregarded simply because they are lean, investment-focused...

D·ASSURE™ Whitepaper: Dawgen Global’s Seven-Pillar Framework for Modern Caribbean Audit Quality

The methodology is here. The framework is yours to apply. Dawgen Global has released the D·ASSURE™ Whitepaper, the standing companion to Article 12 and the series finale of The Caribbean Audit Imperative. The Whitepaper presents D·ASSURE™ — the Dawgen Assurance Standard for Unified Risk-based Engagements — Dawgen Global’s proprietary seven-pillar methodology for conducting modern audit...

The D·ASSURE™ Framework: Dawgen Global’s Seven-Pillar Methodology for Modern Caribbean Audits

This series began with the observation that the Caribbean audit profession is being reshaped by a confluence of forces — revised international standards, sharpened quality-management frameworks, the digitisation of audit techniques, the intersection of cybersecurity with assurance, the arrival of sustainability reporting and its associated assurance regime, and the heightened scrutiny that all of these...

Audit Committee Effectiveness: How Caribbean Boards Can Strengthen Audit Oversight

Ten articles into this series, the focus has been on what the auditor must do. That focus is correct as far as it goes, but it is also incomplete. A competent auditor delivers a competent audit. Whether that audit is then supported, challenged, and integrated into the entity’s governance is the audit committee’s work. The...

Auditing Regulated Entities: What Caribbean Boards Must Know About the Regulator’s Lens

In an ordinary audit, the audit opinion is the principal output and the audit file is the auditor’s working record. In an audit of a regulated entity — a credit union, an insurance company, a securities dealer, a pension fund administrator, a money services business, a bank — the picture changes. The audit opinion is...

Fraud, Going Concern, and the Auditor’s Responsibility: What Caribbean Boards Must Ask

Every time an audit fails publicly, it fails in one of two places. Either a fraud the auditor did not detect comes to light and the audit is criticised for missing it, or an entity that received a clean audit opinion collapses shortly afterward and the audit is criticised for not warning. Across the Caribbean,...

Foo-WLogo

Dawgen Global is an integrated multidisciplinary professional service firm in the Caribbean Region. We are integrated as one Regional firm and provide several professional services including: audit, accounting, tax, IT, risk, HR, performance, M&A, corporate recovery and other advisory services

Where to find us?
img-footer-map
Dawgen Social links
Stay ahead of Caribbean business
Receive our latest insights on tax, regulation, technology and the economy across the region.


    © 2026 Copyright Dawgen Global. All rights reserved.  ·  Privacy Notice  ·  Cookie Policy  ·  Website Terms  ·  Accessibility

    Talk to us