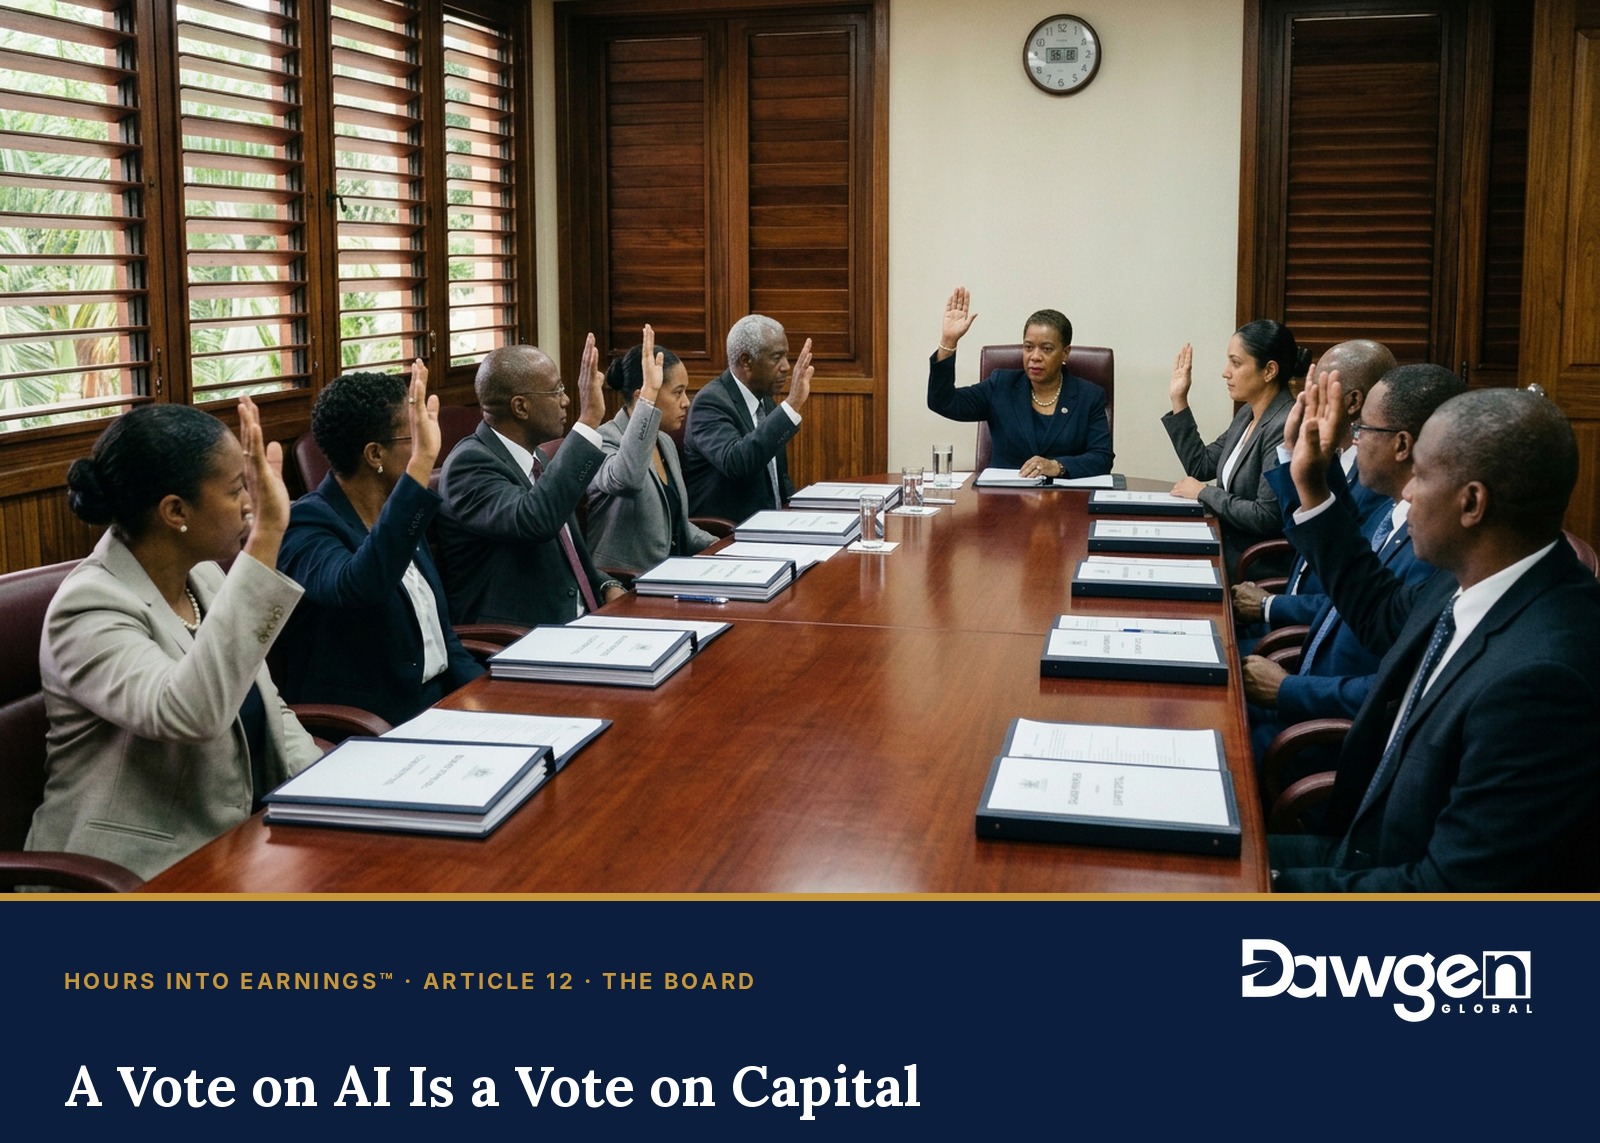
How a board should weigh, fund and hold management to account for AI, as it would any other use of the shareholders’ money, and the series brought together on one page
When a board considers a new warehouse, an acquisition or a fleet of delivery trucks, it knows what to ask. What will it cost? What will it earn, and when? What could go wrong? How will we know if it is working, and what happens if it is not? The proposal arrives with a business case, the board challenges it, and the money is released against milestones.
When the same board considers AI, those questions often disappear. AI arrives as a technology item, presented by the IT function or a vendor, discussed in the language of models, platforms and pilots. The board asks whether the company is keeping up, whether the data is secure and whether staff have been trained. It rarely asks what the shareholders will get back for their money.
This final article of Hours Into Earnings™ argues that the board’s AI question is not a technology question at all. It is a capital allocation question: which uses of the shareholders’ money will earn more than they cost, and how will the board know? The previous eleven articles have each answered part of it. This one puts the parts together into a single method a board can use at its next meeting, and closes the series on one page.
The money is moving faster than the oversight
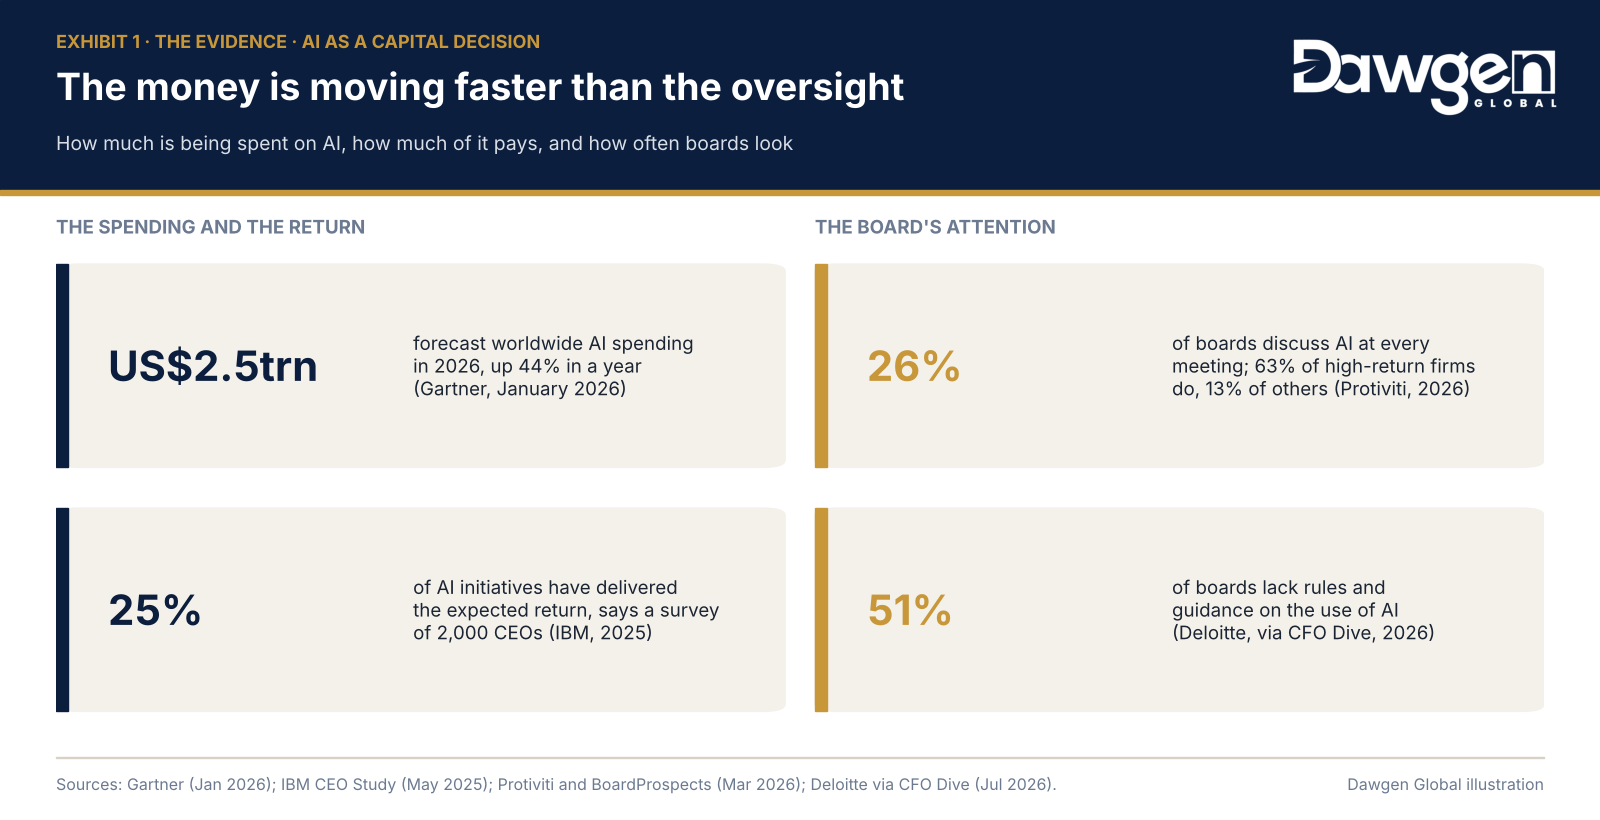
The scale of AI spending makes it one of the largest capital allocation decisions companies are now making. Gartner forecast in January 2026 that worldwide spending on AI would reach about US$2.5 trillion in 2026, an increase of 44% in a single year.
The returns have not kept pace. IBM’s 2025 study of 2,000 chief executives found that only 25% of AI initiatives had delivered the return expected of them, and only 16% had been scaled across the enterprise. Earlier articles in this series have shown the same gap from other angles: most organizations report productivity gains from AI, but far fewer can find them in operating profit.
Board attention is uneven. A global survey of 772 board members and executives by Protiviti and BoardProspects, published in March 2026, found that only 26% of boards discuss AI at every meeting. The difference by results was striking: 63% of organizations reporting high returns from AI put it on every board agenda, against 13% of those reporting low returns. A Deloitte survey of governance professionals reported in July 2026 found that 51% of boards lack rules and guidance on the use of AI.
None of this means boards should spend less on AI. It means they should govern it the way they govern every other large use of capital: with clear expectations, staged commitments and honest review of what was delivered.
What changes when AI is treated as capital
Treating AI as a capital allocation question changes five things about how a board handles it.
Proposals compete for the same money. An AI project should be weighed against the other things the company could do with the same funds: a new branch, a debt repayment, a dividend. If it cannot show a better return than those, it should not be funded simply because it is AI.
Returns are stated in the accounts, not in hours or features. “Staff will save two hours a week” is not a return. “Operating profit will rise by J$40 million a year from the second year, net of running costs, through two posts not refilled” is. The difference is the subject of Article 1.
The full cost is counted. Licence fees are only part of the cost. Usage fees that grow with volume, human review, controls, data work and change management must all be included, as Article 8 showed, or the return will be overstated from the start.
Money is released in stages. Large capital projects are funded in tranches tied to milestones. AI should be too. The first tranche proves the result in one workflow or branch; later tranches scale what has been proved.
There is a lookback. Boards routinely compare the results of past acquisitions and building projects with what was promised. AI programmes deserve the same discipline: a regular review of what each initiative actually delivered, recorded in the AI Earnings Register™ and checked independently.
None of these is new. They are the ordinary disciplines of capital allocation. The problem is that they are seldom applied to AI.
The AI Capital Gate™: five gates between a proposal and the shareholders’ money
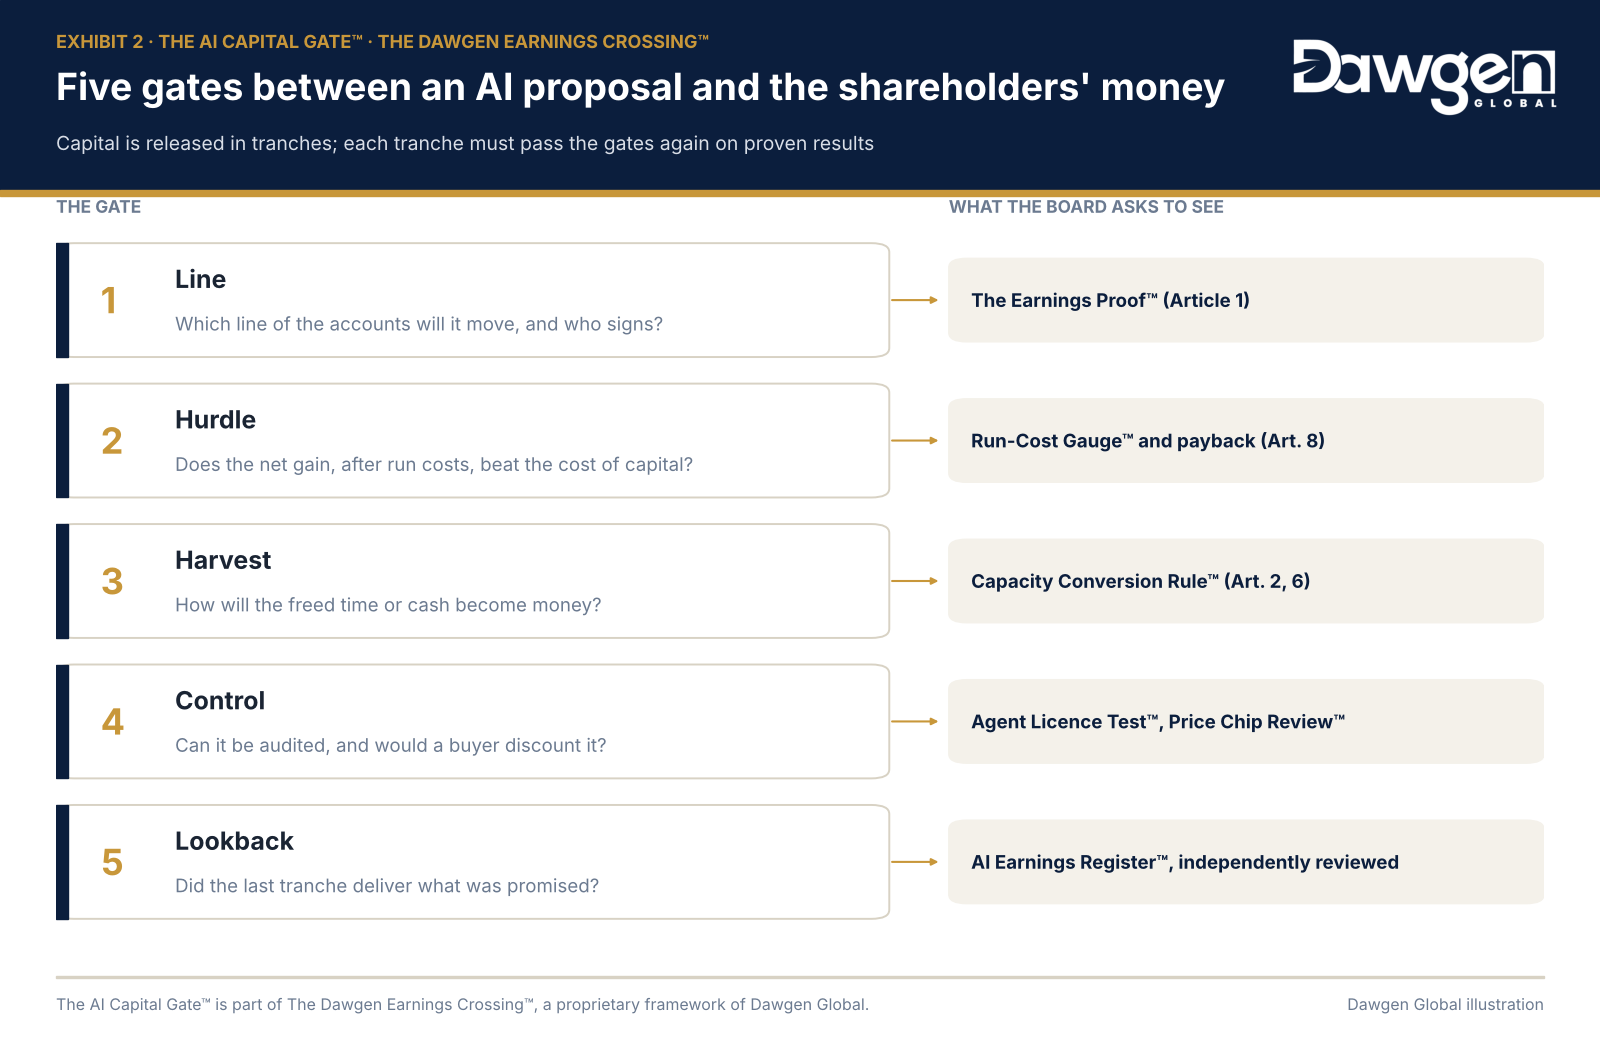
The AI Capital Gate™ is the board’s own instrument within The Dawgen Earnings Crossing™. Every AI proposal above a threshold the board sets must pass five gates before money is committed, and every later tranche must pass them again on proven results. Each gate draws on a device introduced earlier in this series, so management knows exactly what evidence the board expects.
| Gate | The board’s question | The evidence |
| 1. Line | Which line of the accounts will this move, by how much, and who signs for it? | The Earnings Proof™ (Article 1) |
| 2. Hurdle | After all running costs, does the net gain beat the company’s cost of capital, and how quickly does it pay back? | The Run-Cost Gauge™ (Article 8) and a payback period |
| 3. Harvest | How will freed time or released cash become money: avoided hires, retired costs, absorbed growth or repaid borrowing? | The Capacity Conversion Rule™ (Article 2) and the Cash Velocity Count™ (Article 6) |
| 4. Control | Can every AI agent involved be audited, and would a buyer or lender discount what we are building? | The Agent Licence Test™ (Article 9) and the Price Chip Review™ (Article 7) |
| 5. Lookback | For a later tranche: did the last one deliver what was promised? | The AI Earnings Register™, independently reviewed |
Three practical rules make the Gate work.
Set a threshold. Small experiments under an amount the board sets can be approved by management, provided they are recorded in the AI register. Everything above the threshold comes through the Gate.
Fund in tranches. A typical pattern is a first tranche to prove the result in one workflow or location, a second to scale it across the business, and a third to extend it to related workflows. Each tranche passes Gate 5 before the next is released.
Put AI on the agenda, not just in the risk register. A standing quarterly item, built on the AI Earnings Register™, lets the board see which commitments are delivering, which are not, and where to move the money next. The Protiviti finding above suggests the boards of the companies getting the best returns already do this.
The arithmetic: J$300 million requested, J$180 million approved
Consider an illustrative composite: the board of a Caribbean trading and distribution group receives management’s AI plan for the coming year. It asks for J$300 million across six proposals. For the first time, the board applies the AI Capital Gate™.
| Proposal | Requested (J$m) | Expected net gain a year | Gate result | Approved (J$m) |
| Order-to-cash workflow redraw | 50 | About J$56m of operating profit after running costs | All five gates passed | 50 |
| Collections and demand forecasting | 60 | About J$24m of operating profit, plus about J$370m of cash released once | All five gates passed | 60 |
| Pricing and margin leak controls | 40 | About J$28m of operating profit | All five gates passed | 40 |
| Accounts payable agent | 30 | About J$35m of operating profit | Approved on condition it is licensed under the Agent Licence Test™ before going live (Gate 4) | 30 |
| AI assistant licences for all staff | 50 a year | “Two hours saved per person per week” | No route for converting the time into money (Gate 3); returned until a conversion plan exists | 0 |
| Customer service chatbot | 70 | “Better customer experience” | No line of the accounts it moves, and no owner (Gate 1); returned | 0 |
| Total | 300 | 180 |
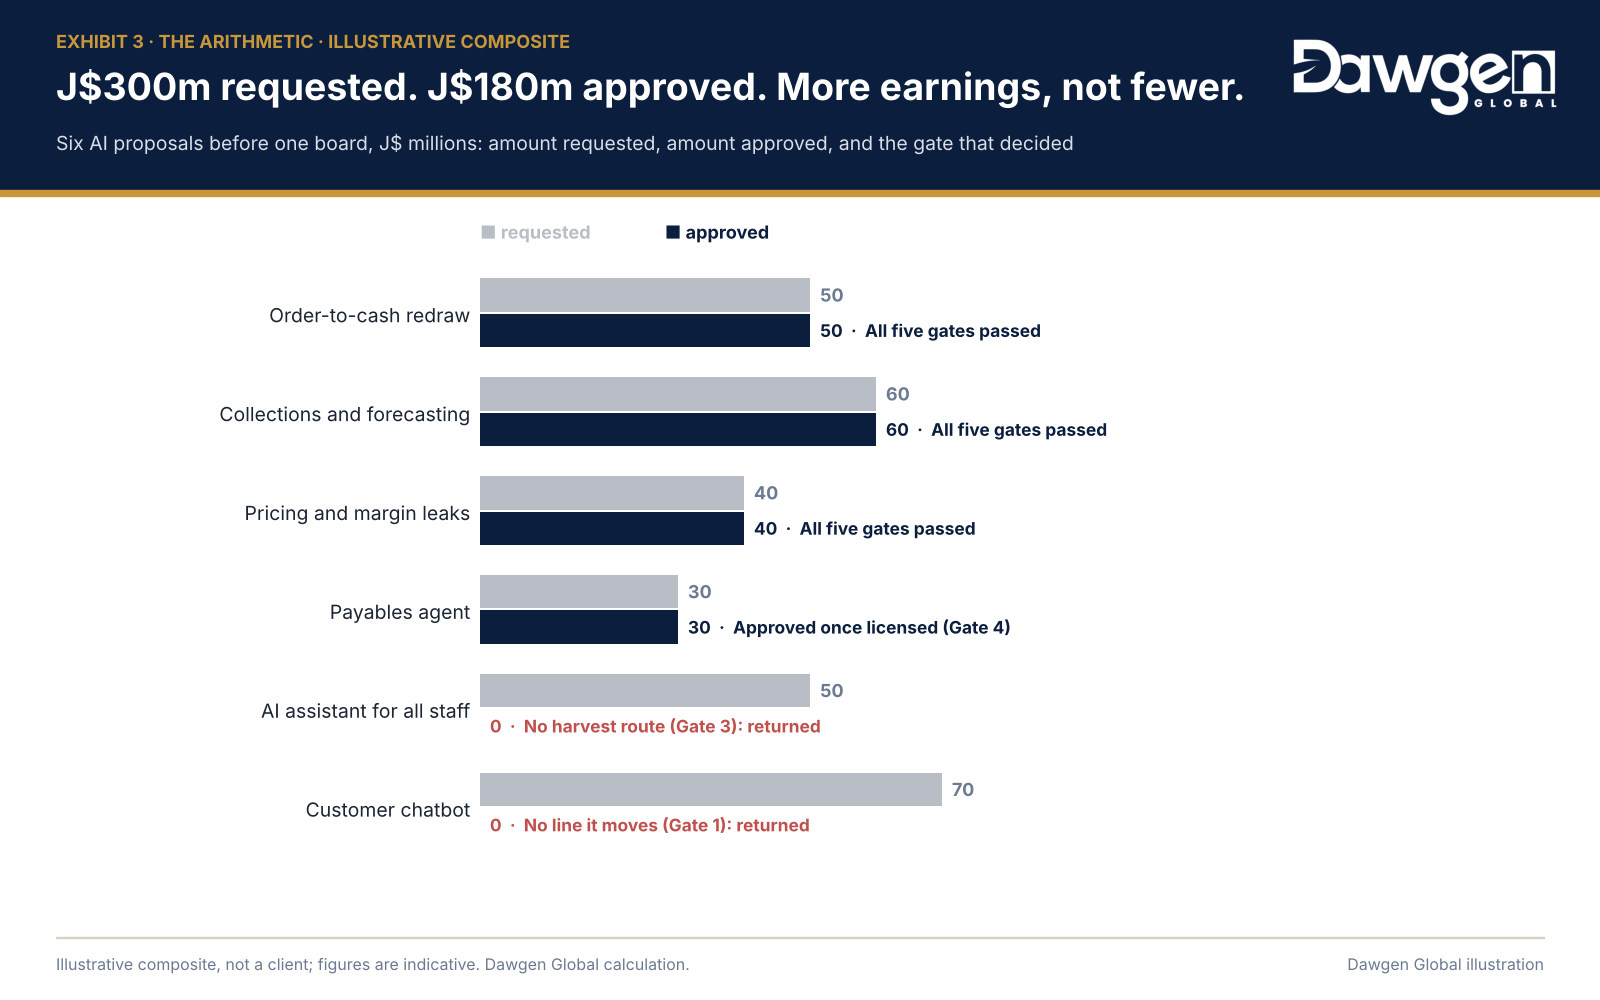
The four approved proposals are expected to add about J$140 million a year to operating profit, after running costs, and release about J$370 million of cash. The board releases the first tranche of each, about 40% of the approved amount, to prove the results in one workflow or region. The rest follows only when each passes Gate 5 at the next quarterly review.
The two returned proposals are not rejected forever. The all-staff assistant may well be worth having, but only once management can show how the time it saves will be converted, through hiring that is avoided or work that is absorbed. The chatbot may return with a clear link to customer retention or service cost. Until then, J$120 million stays available for other uses, including the shareholders’ own.
The board did not spend less on AI because it was cautious. It spent less because it asked the questions it asks of every other use of capital, and two proposals could not yet answer them. The remaining J$180 million is far more likely to reach the accounts.
The composite is illustrative and does not describe any client. Figures are indicative.
The series on one page
Over twelve articles, Hours Into Earnings™ has followed AI value across The Dawgen Earnings Crossing™, from the moment a tool is adopted to the moment its value reaches the shareholders. Each article added one device. Together they form a complete set of questions a company can put to its own AI programme.
| # | Article | The question it answers | The device |
| 1 | Your AI Is Working. Your P&L Hasn’t Noticed. | Which line will it move, and who signs? | Earnings Proof™ |
| 2 | Time Saved Is Not Money Saved | How does freed time become money? | Capacity Conversion Rule™ |
| 3 | Start Where the Cost Is Countable | Where should we start? | Countable Cost Screen™ |
| 4 | The Discount You Didn’t Know You Gave | Where is margin leaking? | Margin Leak Map™ |
| 5 | Revenue You Can Bank, Not Just Forecast | Is the extra revenue real? | Bankable Revenue Test™ |
| 6 | Cash Is the AI Dividend Nobody Counts | How much cash has AI released? | Cash Velocity Count™ |
| 7 | The Multiple Moves When the Risk Does | Would a buyer or lender pay more? | Price Chip Review™ |
| 8 | The Token Bill Is an Operating Line | Does it still earn more than it costs to run? | Run-Cost Gauge™ |
| 9 | An Agent You Cannot Audit Is a Liability | Is every agent under control? | Agent Licence Test™ |
| 10 | Workflow, Not Tools | Have we redesigned the work, or only added tools? | Workflow Redraw™ |
| 11 | Small Enough to Redesign Whole | Are we using the advantage of our size? | One-Table Method™ |
| 12 | The Board’s AI Question Is a Capital Allocation Question | Should the shareholders fund it? | AI Capital Gate™ |
Behind every device sits the same record: the AI Earnings Register™, where each initiative’s claimed and proven value, running cost and controls are kept in one place, measured the same way and reviewed independently. It is the single document that lets management, the board, the auditors and, one day, a buyer see what AI has really done for the business.
The central argument of the series has not changed since the first article. AI makes work faster almost everywhere. It makes companies more valuable only where someone designs, measures and governs the crossing from hours to earnings. That crossing is a management discipline, and in the end it is a board responsibility.
Three questions for the next board meeting
Put three questions on the agenda:
- How much are we committing to AI this year, in total, including running costs, and what return does each commitment promise in operating profit or cash?
- Which of our AI commitments have been funded in stages, and what did the last stage actually deliver against what was promised?
- Where in our board calendar do we review AI as a use of capital, with the same discipline we apply to acquisitions and capital projects?
If the answer to the third question is “nowhere”, the most important AI decision the board can make is to create that place.
A capstone to the series, The Earnings Crossing Scorecard™, will follow: a single page on which a board can score its company across every span of the crossing and see where the next dollar of AI investment should go.
Take the crossing from hours to earnings with Dawgen Global
Dawgen Global’s AI Transformation Advisory takes your organization across The Dawgen Earnings Crossing™, at whatever point you are starting from:
- Earnings Crossing Scan™: a short, fixed-scope review of where AI can release earnings and cash in your business.
- Earnings Crossing Diagnostic™: a whole-company view that sizes the opportunity and sets out a sequenced plan.
- Earnings Crossing Blueprint™: the design of your programme, its measures, controls and board reporting, ready for the AI Capital Gate™.
- Forward-Deployed Crossing Sprints™: our specialists inside your business, redrawing one workflow at a time until the result is proven.
- Earnings Crossing Assurance™ and Dawgen TRUST360™: independent assurance of what your AI earns and continuous governance for your board.
We bring together business advisory, accounting, risk management, cybersecurity, IT and AI transformation specialists across the Caribbean. Fees are customized to each client’s circumstances and agreed deliverables.
Request a scoping conversation: info@dawgen.global · (876) 926-5210 · US 855-354-2447 · dawgen.global
Dawgen Global — Big Firm Capabilities. Caribbean Understanding.
About Dawgen Global
Dawgen Global is an independent, integrated multidisciplinary professional services firm headquartered at 47 Trinidad Terrace, New Kingston, Jamaica, serving more than 15 territories across the Caribbean. Founded and led by Dr. Dawkins Brown, Executive Chairman, the firm is independent and not affiliated with any international network. It delivers a full suite of professional services under one roof: audit and assurance; tax advisory; IT and digital transformation; risk management; cybersecurity; actuarial and insurance regulatory advisory; HR advisory; mergers and acquisitions; corporate recovery; business advisory and strategy; accounting BPO and virtual CFO services; and legal process outsourcing.
The proposition is simple: big-firm capability without the big-firm price. Dawgen Global’s integrated approach is built for the specific complexities and opportunities of the Caribbean market, helping organizations make sharper, better-informed decisions that drive measurable progress.
To explore a partnership, reach out:
- Website: dawgen.global
- Email: info@dawgen.global
- WhatsApp (Global): +1 555-795-9071
- Caribbean offices: +1 876-665-5926 | +1 876-929-3670 | +1 876-926-5210
Related service: Explore how we can help →